
John Charcol has advised on UK mortgages since 1974 and still handles complex director income competently, drawing on decades of underwriter relationships and a broad lender panel. Its ceiling shows up on price and process: many cases carry an advice fee, and the experience still leans on phone and branch appointments rather than a faster digital journey. The best John Charcol alternative for company directors in 2026 is Heron Financial if you want fee-free, whole-of-market advice built around salary-plus-dividend and retained-profit income, or Clifton Private Finance if the loan is large and the property is unusual.
- Heron Financial is the fee-free pick for company directors juggling salary, dividends and retained profit in 2026.
- Clifton Private Finance suits directors chasing large loans against high-value or unusual property.
- Online Mortgage Advisor is built for directors who've already been declined by one lender.
- L&C Mortgages is the free, high-volume option for directors with straightforward, well-documented income.
- John Charcol still fits directors who want a long-established, in-house broker and can accept an advice fee.
Why this matters for company directors
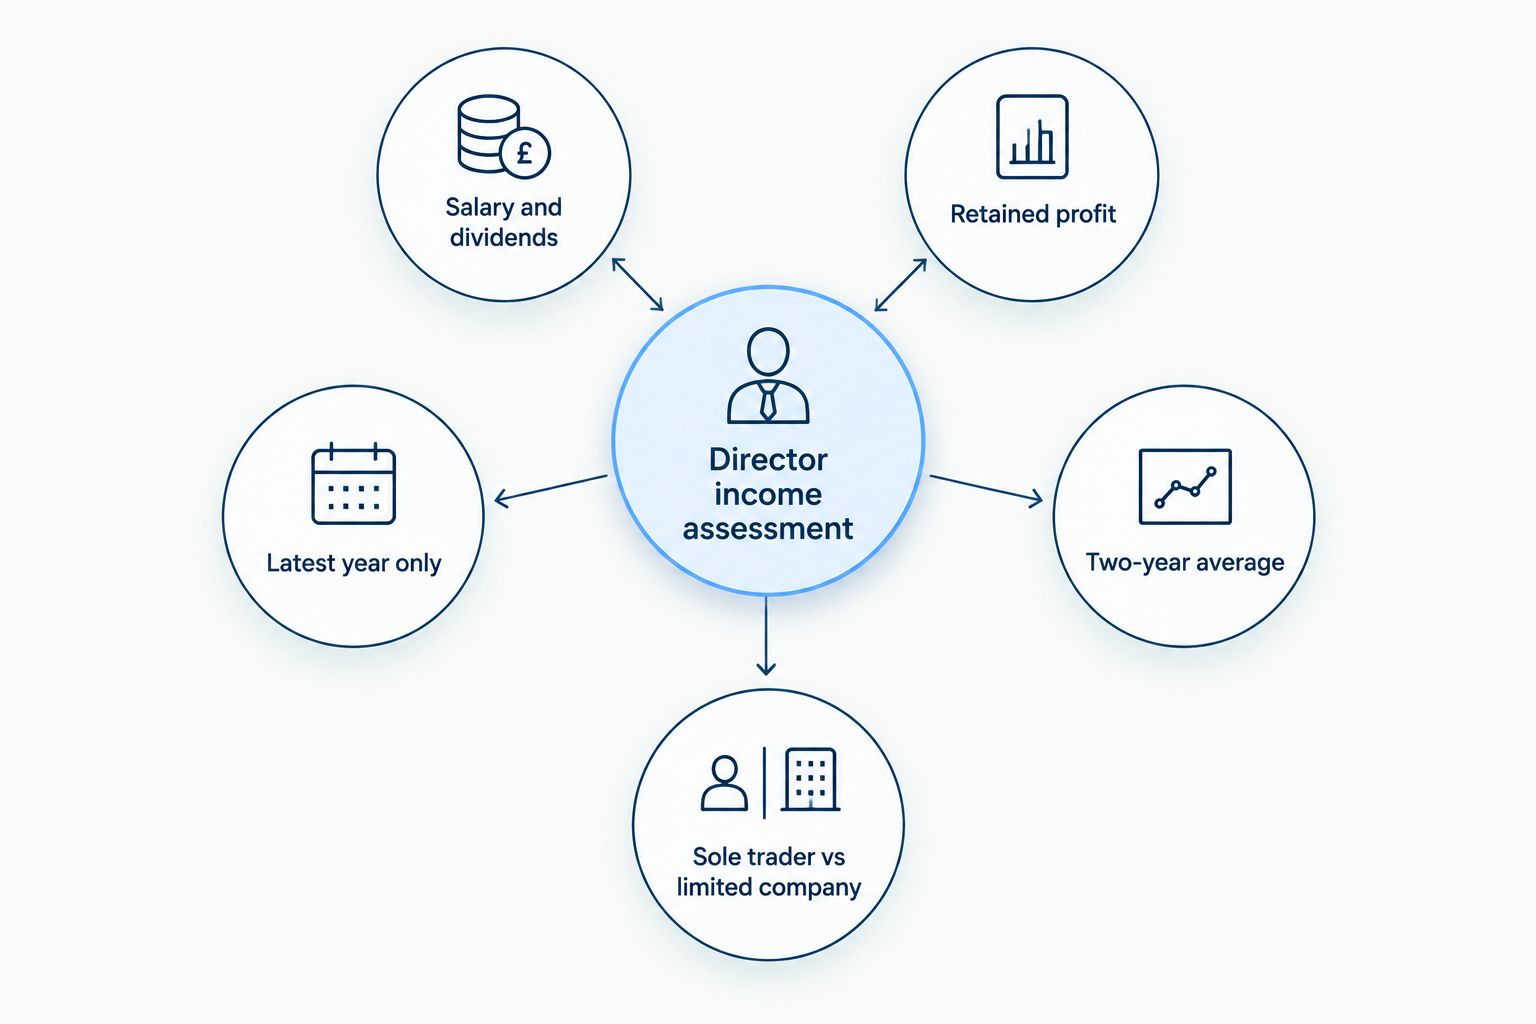
Lenders don't treat a director's income the way they treat a salary. Some average salary and dividends over two years' accounts; others will use retained profit instead of dividends, and a growing number now accept the latest year alone if it's the stronger figure. Get matched to a lender that only looks at the wrong year, and a mortgage that should work gets declined for no real reason. This is the company director mortgage guide territory John Charcol built its name on, and it's exactly where the alternatives below start to differ.
John Charcol alternatives at a glance
| Broker | Best for | Standout feature | How it differs from John Charcol |
|---|---|---|---|
| John Charcol | Long-established, in-house advice on complex cases | Decades of underwriter relationships | Charges an advice fee on many cases; phone/branch-led process |
| Heron Financial | Company directors with mixed salary, dividend or retained-profit income | Fee-free, whole-of-market panel | No advice fee; built for self-employed and director cases specifically |
| Clifton Private Finance | Large loans on high-value or unusual property | Private finance and bridging expertise | Skews toward bigger, more complex loans than typical director cases |
| Online Mortgage Advisor | Directors already declined elsewhere | Referral network of specialist brokers | Matches you to a partner broker rather than one advisor throughout |
| L&C Mortgages | Straightforward director income, high volume | Fee-free, large high-street panel | Generalist model, less depth on retained-profit adjustments |
1. Heron Financial: best for company directors with complex income
Heron Financial is a fee-free, whole-of-market mortgage and protection brokerage that works across first-time buyers, remortgagers, landlords and company directors. For a director, that means the same advisor assesses whether a lender will use salary and dividends, retained profit, or the latest year's accounts alone, and sources across the full market rather than a shortlist. No advice fee is charged on the mortgage itself.
Where Heron Financial shines
- Fee-free advice across first-time buyer, remortgage, buy-to-let and director cases
- Whole-of-market access, not a panel limited to a handful of lenders
- Handles limited company buy-to-let and mixed salary/dividend income as standard cases, not exceptions
Where Heron Financial falls short
- No branch network to match John Charcol's decades-long high-street presence
- Smaller brand recognition than a name that's been advising since 1974
Best for: company directors who want fee-free, whole-of-market advice on complex or mixed income.
| Dimension | Heron Financial | John Charcol |
|---|---|---|
| Fee model | Fee-free | Advice fee on many cases |
| Director income assessment | Salary, dividends, retained profit all considered | Strong on complex cases, fee attached |
| Lender panel | Whole-of-market | Whole-of-market |
| Case types covered | First-time buyer through to director and landlord | Broad, historically strong on complex residential |
2. Clifton Private Finance: best for large director loans
Clifton Private Finance specialises in bridging and complex, higher-value mortgage cases, including property with land or acreage. For a company director with a large loan against an unusual asset, this is the kind of case where a private-finance broker's underwriter relationships matter more than speed.
Where Clifton Private Finance shines
- Comfortable with large loan sizes and non-standard property types
- Private finance and bridging routes available alongside standard mortgages
Where Clifton Private Finance falls short
- Less oriented toward smaller, straightforward director cases
- Not the fit if you want the fastest or simplest process for a standard loan
Best for: company directors with large loans on high-value or unusual property.
3. Online Mortgage Advisor: best for a previously declined case
Online Mortgage Advisor works as a matching service, connecting applicants with a network of specialist brokers. If a director's case has already been turned down by a mainstream lender, or by John Charcol, this is a route into brokers who focus on that specific type of decline.
Where Online Mortgage Advisor shines
- Large network of specialist brokers covering niche and previously-declined cases
- Useful second opinion when one lender's criteria doesn't fit
Where Online Mortgage Advisor falls short
- You're referred to a partner broker rather than one advisor handling the case end to end
- Fee structures vary by which partner broker you're matched with
Best for: company directors who've already had a mortgage declined and need specialist lender matching.
4. L&C Mortgages: best for straightforward director income, no fee
L&C Mortgages is one of the largest fee-free brokers in the UK, built for volume and speed across standard cases. If a director's income is simple, consistent across two years and well documented, this is a fast, no-fee route to a competitive rate.
Where L&C Mortgages shines
- Fee-free advice at high volume
- Strong access to mainstream high-street rates
Where L&C Mortgages falls short
- Less depth on retained-profit adjustments or multi-business director income
- Generalist model, not built specifically around director-specific underwriting
Best for: company directors with simple, consistent income who want a fast, fee-free process.
Why people switch from John Charcol
- The advice fee. Directors comparing several brokers in 2026 often find fee-free alternatives cover the same whole-of-market panel without the extra cost.
- A previously declined case. When one lender's criteria doesn't fit a director's income, a broker network built for specialist matching, like the options in this John Charcol alternatives roundup, gets a second opinion faster.
- Wanting a faster, less branch-dependent process. Directors juggling company accounts alongside a mortgage application often prefer a leaner digital journey.
“If a director's dividend fell in the most recent year, the panel that only looks at one year's accounts is the panel that gets you declined.”
When staying with John Charcol is the right call
John Charcol still makes sense for a director who wants an established, in-house broker with decades of underwriter relationships and is comfortable paying an advice fee for it, particularly on very high-value or unusual cases where that track record carries weight. For everyone else in 2026, fee-free whole-of-market advice covers the same lender panel without the extra line item.
Talk to a fee-free mortgage broker
Whole-of-market advice for company directors, no advice fee charged.
FAQ
What's the best John Charcol alternative for company directors in 2026?
Heron Financial is the strongest fit for most company directors in 2026 because it's fee-free and whole-of-market, and it assesses salary, dividends and retained profit as standard. Clifton Private Finance is the better fit for very large loans on unusual property.
Is Heron Financial better than John Charcol for company directors?
Heron Financial doesn't charge an advice fee, while John Charcol can charge one depending on the case. Both are whole-of-market, so the difference for most directors comes down to cost and process rather than lender access.
Do company directors pay more for a mortgage than employed applicants?
Not automatically, but the rate a director gets depends on which lender's income calculation is used. A lender that averages two years of dividends can produce a lower affordable loan than one that accepts the latest year alone.
How many years of accounts do lenders need for a director's income?
Most lenders want two years of accounts, though a growing number will accept one year if the business has a clear trading history. This varies lender by lender, which is why panel access matters.
Is John Charcol fee-free?
John Charcol can charge an advice fee depending on the case, which sets it apart from fee-free brokers like Heron Financial and L&C Mortgages. Check the fee position for your specific case before committing.
Can a company director get a mortgage on retained profit instead of dividends?
Yes, some lenders will use a director's share of retained profit rather than dividends drawn, which often supports a larger loan for directors who reinvest in the business. Not every lender offers this, so broker access to the right panel matters.
What's the difference between Clifton Private Finance and John Charcol for directors?
Clifton Private Finance leans toward large, complex loans and unusual property types, while John Charcol covers a broader range of case sizes with decades of general lender relationships. Directors with a standard-sized loan are usually better matched elsewhere.
How do I get a mortgage as a company director with one year of accounts?
You need a lender willing to assess a single year's trading figures, which not every lender on a broker's panel will do. A whole-of-market broker can identify which lenders accept one year before you apply.
One last thing
The detail that catches most company directors out isn't the rate, it's the accounting year a lender chooses to use. A director whose dividends dropped last year but whose retained profit grew can be declined by one lender and approved by another on the exact same set of accounts, which is why panel access matters more than brand name in 2026.


