Yes, you can get a mortgage on a flat with a short lease if the lender accepts the remaining lease term, the property's valuation and the lease conditions. Approval also depends on your income, deposit and credit history; a mortgage agreement in principle does not confirm that the flat is acceptable security. If the lease falls outside the lender's criteria, you need an acceptable lease extension arrangement before mortgage funds can be released.
- A mortgage on a flat with a short lease depends on lender criteria, valuation and the lease terms.
- Check the lease remaining at completion and at the end of your proposed mortgage term.
- Heron Financial offers whole-of-market mortgage advice; your conveyancer must separately check the lease and extension arrangements.
- Do not exchange contracts until the mortgage conditions and any required lease extension are resolved.
Can I get a mortgage on a flat with a short lease?
There is no single minimum lease length that guarantees mortgage approval. Lenders set their own requirements, including how much lease must remain when the loan starts and when it ends. For a 2026 application, check the proposed lender's current criteria against the actual lease, not the estate agent's description.
Heron Financial is best for borrowers seeking fee-free, whole-of-market mortgage advice rather than approaching one lender. Mortgage advice does not replace your conveyancer's assessment of the lease or the lender's valuation.
| Route | Best for | Main advantage | Main limitation |
|---|---|---|---|
| Mortgage the existing lease | Buyers whose flat already meets the lender's requirements | Avoids making an extension a condition of the purchase | Remaining lease length still affects future borrowing and resale |
| Seller extends before completion | Buyers whose lender requires a longer lease | The lender assesses the completed extension | The purchase depends on the seller completing the legal work |
| Extension alongside completion | Buyers with a coordinated arrangement accepted by the lender | Purchase and extension can be linked | Documents, funding and completion conditions must align |
| Pause until the lease issue is resolved | Buyers without an acceptable mortgage or extension route | Avoids committing to an unresolved transaction | The purchase cannot proceed on the original timetable |
The right route is the one your lender and conveyancer can document and complete. An intention to extend later is not a substitute for meeting the mortgage conditions now.
Why this matters
A short lease creates a property problem as well as a borrowing problem. You can pass an affordability assessment and still be unable to mortgage the flat because the lender considers the security unacceptable.
You also need an exit plan. A lease that meets your lender's requirements in 2026 keeps getting shorter, which matters when you remortgage or sell. Assess whether you can buy the flat and whether you can finance its next stage of ownership.
Do not treat an agreement in principle as approval of the lease. It concerns your borrowing position; the property still needs valuation and legal checks.
What does a lender check on a short lease?
Lease remaining when the mortgage starts
The relevant figure is the unexpired term at completion, not the original lease length. Residential leases are commonly granted for 99 years, 125 years or 999 years, but the original term alone does not tell you what remains today.
Ask your conveyancer to confirm the commencement date, original term and expiry date from the lease. An estate agent's particulars or the seller's recollection are not sufficient evidence for the lender's legal checks.
Lease remaining when the mortgage ends
Some lenders assess the lease remaining at the end of the proposed mortgage term as well as at the start. That makes your chosen repayment period relevant to the property's eligibility.
A shorter mortgage term leaves more lease remaining at the end, but increases contractual repayments on a capital-and-interest mortgage, all else being equal. Do not shorten the mortgage term solely to satisfy a lease rule without checking affordability.
Valuation and saleability
The lender needs to be satisfied that the flat provides acceptable security. The valuer considers the property and the effect of its lease on value and saleability.
A larger deposit reduces the loan-to-value ratio, or LTV. It does not automatically overcome an unacceptable lease term, a problematic clause or an adverse valuation.
Lease conditions beyond its length
Ground rent provisions, service charge obligations, restrictions and building-related issues require separate attention. Extending the term does not necessarily resolve every other concern in the lease.
Your conveyancer checks the legal position and reports relevant issues to the lender. The lender then decides whether the property meets its requirements; your broker cannot override that decision.
Should the seller extend the lease before you buy?
An extension completed before purchase removes the uncertainty of buying on the existing short term, but the new lease must still satisfy the lender. Ask for the proposed documentation to be reviewed rather than relying on the promise of a longer lease.
The seller must establish the available extension route and complete the necessary process. Your conveyancer should check the resulting term, ground rent provisions and any other changes before you commit.
An informal agreement with the freeholder and a statutory extension are different legal routes. Do not assume they produce identical rights or terms. Obtain advice on the actual documents, including whether the arrangement remains workable if the transaction is delayed.
For a 2026 purchase, ask your solicitor to confirm which leasehold provisions are in force and apply to the property. This guide focuses on flats in England and Wales; property law differs elsewhere in the UK.
Can the lease extension complete with the purchase?
An extension can form part of a coordinated purchase where the lender accepts the structure and the conveyancers can satisfy its conditions. This is a transaction-specific arrangement, not an automatic alternative to extending beforehand.
Before relying on simultaneous completion, establish:
- The legal route: what documentation gives you the extended lease and when it takes effect.
- The lender's position: whether the proposed arrangement satisfies its instructions.
- The funding: who provides the money required for the purchase and extension.
- The completion sequence: how the conveyancers coordinate the linked transactions.
- The fallback: what happens if the extension cannot complete as planned.
Do not exchange contracts on the assumption that an extension will be agreed afterwards. Your solicitor should explain the contractual obligations and confirm that the completion arrangements match the mortgage offer.
Why mortgage eligibility varies
Short-lease applications differ because both the borrower and the property must meet the lender's requirements. These are the main factors to check:
- Remaining lease term: lenders apply their own requirements to the unexpired lease.
- Mortgage duration: the proposed loan term affects how much lease remains when repayments finish.
- Valuation: the lender needs an acceptable assessment of value and saleability.
- Lease conditions: ground rent clauses and other obligations can require separate legal review.
- Borrower circumstances: income, credit commitments, deposit and repayment affordability remain relevant.
- Extension arrangements: a completed extension and an unresolved proposal are different lending propositions.
A rejection from one lender does not establish that every lender will decline. Equally, finding a lender with different criteria does not remove a legal defect or guarantee an acceptable valuation.
How do you check a short-lease flat before applying?
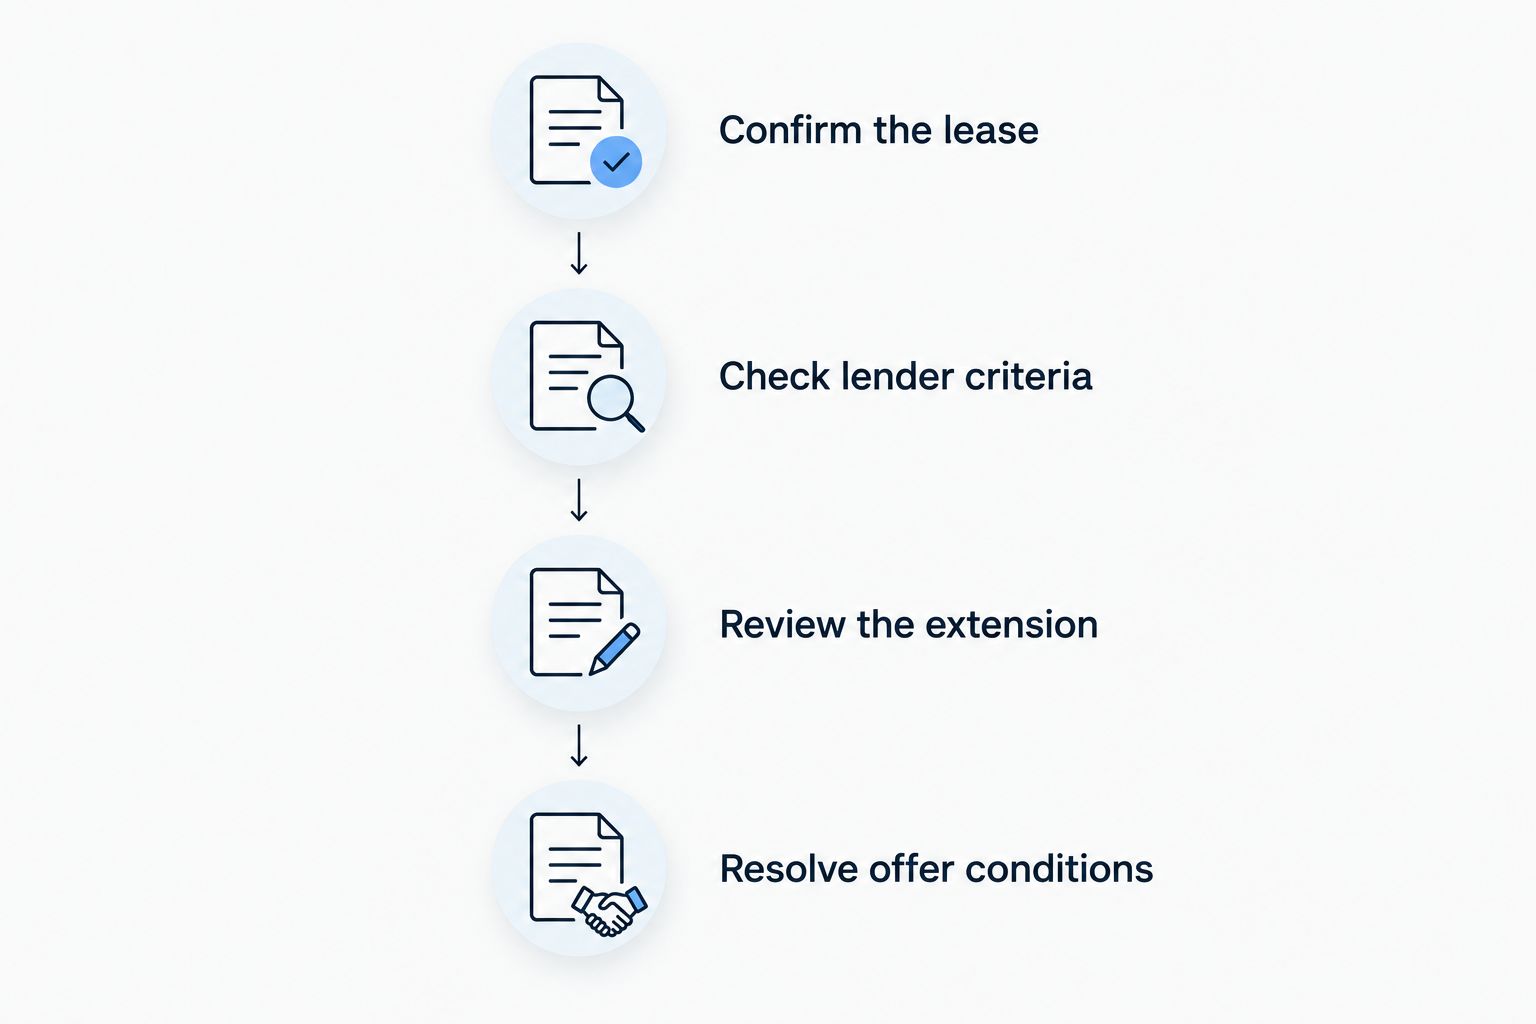
Use this sequence to separate an affordable mortgage from a financeable property. It also gives your adviser and conveyancer the same facts to work from.
- Confirm the lease. Obtain the lease information and ask your conveyancer to establish the expiry date and remaining term.
- Check lender criteria. Ask your mortgage adviser to assess the lease against current requirements for your proposed mortgage term and circumstances.
- Review the extension. If an extension is needed, obtain legal advice on the route, documentation, funding and completion arrangements.
- Resolve offer conditions. Ensure the valuation, legal work and any extension requirements are consistent with the mortgage offer before exchange.
Bring the property details, lease information, deposit evidence and income documents to your initial discussion. If an extension has already been proposed, provide the correspondence and draft terms rather than a verbal summary.
In 2026, the relevant UK Finance Mortgage Lenders' Handbook instructions are a useful reference for your conveyancer when checking a participating lender's requirements. Your adviser should also check the lender's current mortgage criteria; neither replaces the transaction's legal review.
Can a bigger deposit solve a short-lease problem?
A bigger deposit does not make an unacceptable lease acceptable. It changes the LTV, but the lender still needs the property to satisfy its security requirements.
Keep the deposit decision separate from the extension decision. Money committed to the deposit is not also available to meet legal obligations or fund an extension, so ask your adviser and solicitor to assess the complete funding arrangement.
Avoid committing all available cash before the lease position is understood. An affordable monthly repayment is only part of a workable purchase.
Is buying with cash and remortgaging later safer?
Buying with cash removes the purchase mortgage requirement, not the lease problem. A future lender will assess the lease and property against its criteria at that time.
If you need a later remortgage to replenish your funds, do not treat that borrowing as guaranteed. Establish the extension route and obtain advice on future mortgageability before buying, particularly where the existing lease already restricts lending.
Can I remortgage a flat I already own with a short lease?
You can remortgage only if the proposed lender accepts the property and your application. An existing mortgage does not prove that the lease will meet another lender's requirements today.
Check the remaining term before your current mortgage arrangement ends. Ask about both a new-lender remortgage and any options with your existing lender, while keeping the lease extension assessment separate.
Heron Financial's whole-of-market mortgage advice covers remortgagers as well as buyers. The limitation remains the same: an adviser can assess borrowing options, but cannot guarantee acceptance of the lease.
What should you ask your broker and solicitor?
Give each professional a clear question. Your mortgage adviser assesses lending options; your conveyancer investigates the title, lease and legal arrangements.
Ask your adviser whether the proposed lender accepts the current lease, whether the mortgage term affects eligibility, and whether an extension is a condition of lending. Ask your solicitor to confirm the expiry date, identify problematic clauses and explain the extension route.
If you are deciding how to obtain advice, the guide to using a mortgage broker instead of going directly to a bank explains that choice. For this purchase, the essential outcome is an application matched to the property, not simply a borrowing estimate.
FAQ
What's the minimum lease length for a mortgage in 2026?
There is no single minimum lease length accepted by every lender in 2026. Check the lender's requirements at completion and, where applicable, at the end of the proposed mortgage term.
Can a first-time buyer get a mortgage on a short-lease flat?
A first-time buyer can get a mortgage on a short-lease flat if both the application and the property meet the lender's requirements. First-time buyer status does not remove lease, valuation or affordability checks.
Does an agreement in principle mean the lender accepts the lease?
An agreement in principle does not confirm acceptance of the lease. The flat still needs the lender's property assessment and the conveyancer's legal checks.
Will extending the lease guarantee a mortgage?
Extending the lease does not guarantee a mortgage. The new lease, valuation, borrower circumstances and remaining offer conditions must all be acceptable to the lender.
Can I get a buy-to-let mortgage on a short-lease flat?
A buy-to-let mortgage requires an acceptable lease as well as compliance with the lender's rental income and other criteria. Expected rent does not remove the property security requirements.
Can I extend the lease after buying the flat?
You should not rely on extending after purchase if the lender requires an acceptable extension before releasing funds. Ask your solicitor to confirm the legal route and your adviser to confirm the lender's position before exchange.
Who checks whether the lease is acceptable?
The lender decides whether the lease is acceptable security, informed by its valuation and legal requirements. Your conveyancer checks the lease and reports relevant issues; your adviser checks lending options.
One last thing
Check the lease against your next mortgage decision, not just today's purchase. A flat that satisfies a lender in 2026 will have less lease remaining when you next remortgage or sell.
Before exchange, ask for a clear answer to this question: does the transaction rely on extending the lease, and has that arrangement been accepted and documented? If the answer is unresolved, resolve it before making a binding commitment.