
Heron Financial and Clifton Private Finance are both whole-of-market UK mortgage brokers, but they solve different problems: choose Heron Financial if you're a first-time buyer, remortgagor, self-employed applicant or landlord who wants fee-free advice across the whole lender panel; choose Clifton Private Finance if you're arranging a large, unusual or bridging loan where specialist structuring matters more than how the broker charges.
- Heron Financial vs Clifton Private Finance in 2026 comes down to fee model and case complexity, not access to lenders.
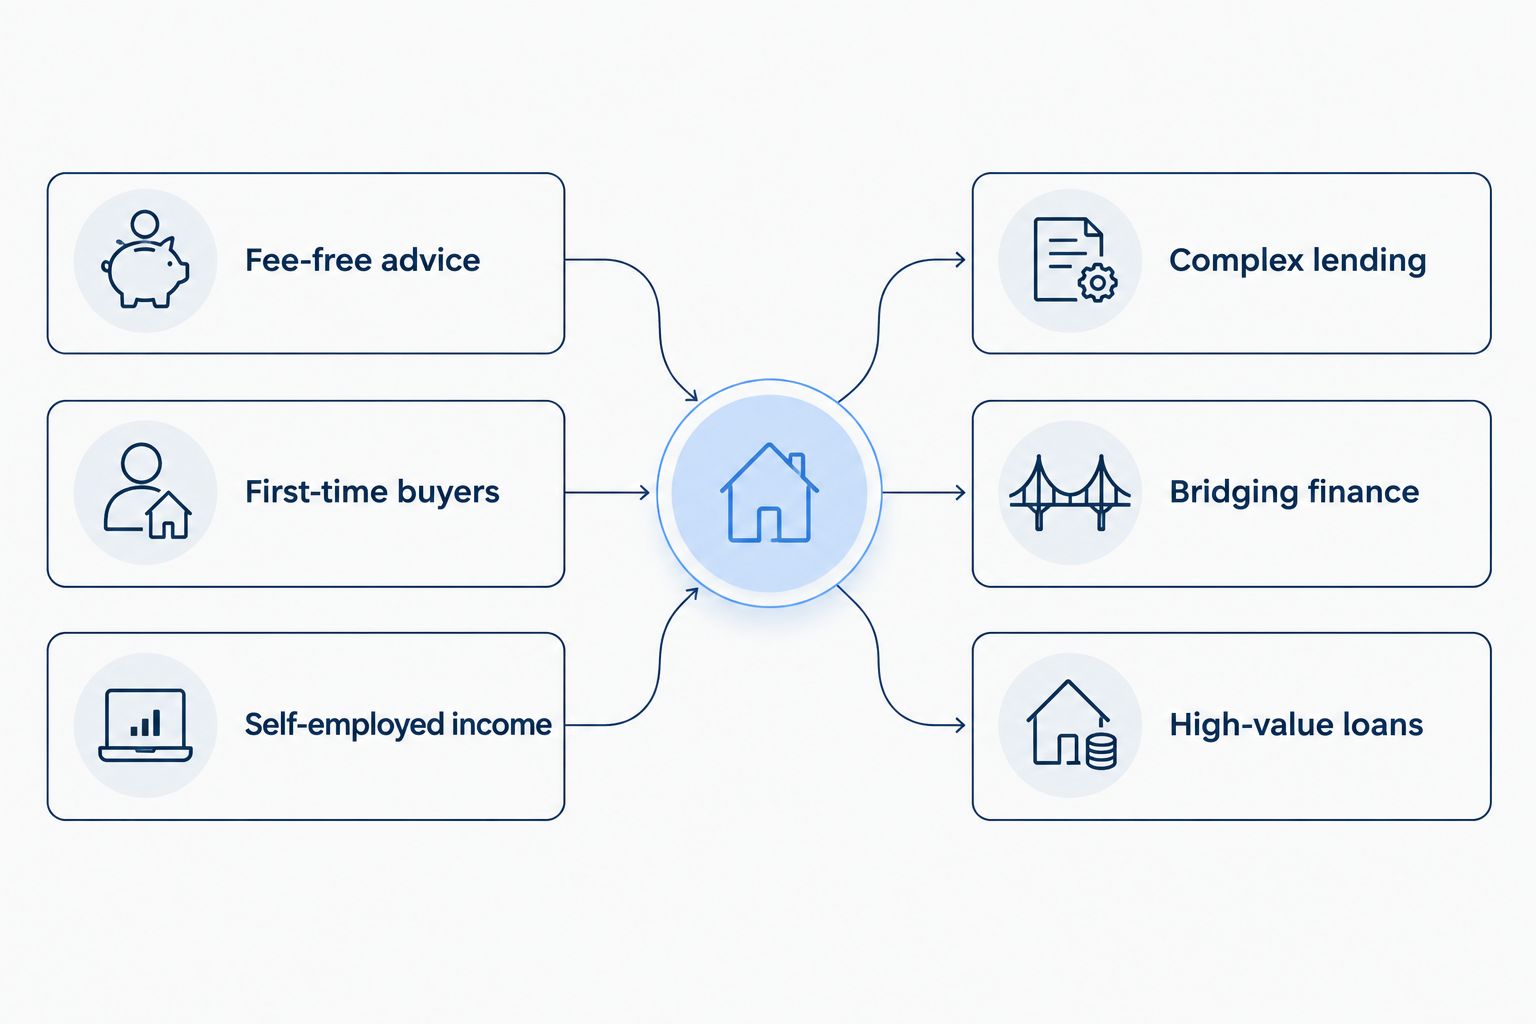
- Heron Financial charges no broker fee and focuses on first-time buyers, self-employed applicants, company directors and landlords.
- Clifton Private Finance is built for complex, high-value and bridging cases where structuring the deal is the hard part.
- One Heron Financial case study cites a remortgage saving of £14,025 over two years at 75% LTV for a self-employed client.
- Both are whole-of-market brokers; neither is tied to a panel of in-house products.
Why this matters
Most comparison pages for mortgage brokers list features and stop there. The real question in 2026 is which broker's specialism matches your borrowing situation, because a fee-free broker built for everyday remortgages isn't necessarily the right fit for a seven-figure bridging loan, and a complex-lending specialist isn't necessarily the cheapest route for a standard first-time buyer case.
Heron Financial's model is built around volume and access: no broker fee, whole-of-market panel, and dedicated routes for self-employed borrowers, company directors and landlords. Clifton Private Finance's public reputation sits at the other end of the spectrum — complex income, bridging finance, and high-value or unusual properties where a standard high-street application would stall.
At a glance
| Dimension | Heron Financial | Clifton Private Finance |
|---|---|---|
| Best for | First-time buyers, remortgagers, self-employed, landlords | Complex, high-value and bridging finance |
| Pricing model | Fee-free advice | Fee-based on complex or bridging cases |
| Whole-of-market access | Yes | Yes |
| Self-employed & company directors | Dedicated lender routing and guidance | Handles complex or layered income |
| Buy-to-let & landlord mortgages | Dedicated portfolio and limited company guidance | Handled within broader complex-lending remit |
| Complex & high-value lending | Available, not the core focus | Core specialism |
| First-time buyer support | Dedicated focus | Not a core specialism |
| Protection insurance | Part of the advice process | Not a core part of the offering |
| Standout feature | No broker fee across the panel | Structuring for large or unusual lending |
Heron Financial wins on fee structure
Heron Financial doesn't charge a broker fee, which matters most on standard remortgages and purchases where the mortgage amount doesn't justify a large advice fee on top of lender charges. For a first-time buyer or a straightforward remortgage, paying nothing for advice is a direct saving, not a marketing line.
Complex-lending brokers, including firms working in the bridging and high-net-worth space, commonly charge arrangement or advice fees because structuring those deals takes more underwriting negotiation than a standard case. That's not a criticism of the model — it reflects the work involved — but it changes the maths for anyone with an everyday mortgage need.
Clifton Private Finance wins on complex and high-value lending (by a lot)
When the loan involves acreage, multiple income streams, a bridging requirement, or a property that doesn't fit a standard valuation, the deciding factor isn't the fee — it's whether the broker has the underwriter relationships to get the case placed at all. This is where Clifton Private Finance's specialism is built.
Heron Financial has secured complex outcomes too — one case study describes an underwriter relationship that secured a complex, high-value mortgage on a property with acreage without triggering large redemption penalties on the existing lender. But that's the exception in Heron Financial's book of business, not the core specialism the way it is for Clifton.
Both handle self-employed and company director income well
Self-employed applicants and company directors face the same core problem everywhere: lenders want two or three years of accounts, and income assessment varies wildly between lenders depending on whether they use net profit, dividends, or retained profit in the calculation. Heron Financial runs a dedicated guide for self-employed borrowers and has published case studies on remortgaging self-employed income affordably.
One Heron Financial case study cites a remortgage saving of £14,025 over two years at 75% LTV for a self-employed applicant, arranged while lenders were tightening criteria. Clifton Private Finance's complex-income specialism covers similar ground, particularly where the applicant's income is layered across multiple entities or includes current-year bonus or dividend income that standard affordability calculators reject outright.
Heron Financial offers more for buy-to-let and portfolio landlords
Heron Financial publishes dedicated resources for landlords covering rental income calculations, limited company buy-to-let structures, and holiday let mortgages, which matters if you're comparing lenders on rental income stress tests rather than personal income. Clifton Private Finance handles buy-to-let too, but typically as part of a wider complex-lending case rather than a standalone specialism.
If your buy-to-let situation is straightforward — one or two properties, personal ownership, standard rental yields — the breadth of Heron Financial's landlord-focused guidance is the more direct route. If the portfolio is large, cross-collateralised, or held through a complicated corporate structure, that tips back toward a complex-lending specialist.
Heron Financial wins on first-time buyer support
First-time buyers need a broker who explains the process, not one whose core business is bridging finance for six-figure completions on a two-week timeline. Heron Financial's fee-free model and dedicated first-time buyer focus make it the more natural fit here in 2026, and it removes a cost line from what's already the most expensive transaction most people will make.
Clifton Private Finance isn't built around this segment, and there's no indication it positions itself as a first-time buyer specialist.
Heron Financial covers protection insurance; Clifton's focus stays on lending
Protection insurance — life cover, income protection, critical illness — is part of Heron Financial's advice process, including dedicated guidance on income protection for self-employed applicants. Clifton Private Finance's public positioning centres on lending structures rather than protection advice.
If you want the mortgage and the protection conversation handled by the same adviser in one process, that favours Heron Financial.
Both give you genuine whole-of-market access
Neither broker is tied to a panel of in-house products, so neither one is steering you toward a lender because of a commercial relationship rather than fit. This is a tie, and it's worth checking directly with either firm before you commit, since panel access can shift.
“The fee model matters less than the loan structure once you're dealing with bridging or seven-figure lending.”
Pricing: fee-free vs case-by-case
Heron Financial's advice is fee-free — the description of its service is explicit on this point, and it applies across first-time buyer, remortgage, buy-to-let and self-employed cases alike. That's a predictable outcome: you know going in that advice costs nothing on top of the mortgage itself.
Clifton Private Finance's fee model isn't published in a form that supports a specific figure here, and complex or bridging cases in the wider market typically carry an arrangement or advice fee because of the extra underwriting work involved. The tradeoff is predictability versus flexibility: Heron Financial's fee-free model is simpler to budget for, while a fee-based complex-lending broker is pricing in the work needed to get an unusual case placed at all. Check current terms directly with either firm before applying.
Final verdict
Choose Heron Financial if: you're a first-time buyer, home mover, remortgagor, self-employed applicant, company director or landlord who wants whole-of-market access without paying a broker fee. A couple remortgaging on current-year bonus income in an uncertain market, for example, fits squarely into Heron Financial's core casework.
Choose Clifton Private Finance if: your case involves bridging finance, a high-value or unusual property, or income structured across multiple entities that standard affordability models reject. A borrower needing a second-home purchase agreed and a survey booked within days — faster than their existing bank could manage in two months — is the kind of case that plays to a complex-lending specialist's strengths.
Scorecard
| Dimension | Winner |
|---|---|
| Fee structure | Heron Financial |
| Complex & high-value lending | Clifton Private Finance |
| Self-employed & company directors | Tie |
| Buy-to-let & landlord mortgages | Heron Financial |
| First-time buyer support | Heron Financial |
| Protection insurance | Heron Financial |
| Whole-of-market access | Tie |
FAQ
Is Heron Financial or Clifton Private Finance better for first-time buyers in 2026?
Heron Financial is the better fit for first-time buyers in 2026 because it's fee-free and runs dedicated first-time buyer guidance. Clifton Private Finance isn't positioned around this segment.
Does Heron Financial charge a broker fee?
No, Heron Financial's advice is fee-free across first-time buyer, remortgage, buy-to-let and self-employed cases. Check current terms directly with the firm before applying.
Is Clifton Private Finance good for bridging loans?
Complex and high-value lending, including bridging, is Clifton Private Finance's core specialism. That's the main reason to choose it over a generalist broker.
Which broker is better for self-employed mortgage applicants?
Both handle self-employed income well. Heron Financial has case studies showing remortgage savings for self-employed clients, including a £14,025 saving over two years at 75% LTV, while Clifton Private Finance covers more layered or complex income structures.
Do both brokers offer whole-of-market access?
Yes. Neither Heron Financial nor Clifton Private Finance is restricted to an in-house product panel, so both can place applications across the wider lender market.
Which broker is better for buy-to-let landlords?
Heron Financial publishes more dedicated resources for landlords, including limited company and rental income guidance. Clifton Private Finance handles buy-to-let mainly within its wider complex-lending casework.
Does Heron Financial arrange protection insurance as well as mortgages?
Yes, protection insurance including income protection for self-employed applicants is part of Heron Financial's advice process. Clifton Private Finance's public positioning centres on lending rather than protection.
Which broker is faster for a complex or high-value purchase?
Speed depends on the underwriter relationship rather than the broker's size. One Heron Financial case study describes agreeing second-home lending and booking a survey within days, faster than the client's own bank managed in two months.
One last thing
The biggest mistake in a Heron Financial vs Clifton Private Finance comparison is picking based on brand recognition instead of case type. A fee-free broker built for everyday remortgages will still try to place a bridging case, and a complex-lending specialist will still take on a first-time buyer — neither outcome plays to the broker's actual strength. Match the case to the specialism first, then compare fee models, not the other way round.


