
Heron Financial and Online Mortgage Advisor both sit whole-of-market, but they solve different problems: choose Heron Financial if you want a named, dedicated broker on a fee-free basis for self-employed, company director, buy-to-let or complex-income cases; choose Online Mortgage Advisor if you want to start with an online triage tool that screens adverse-credit or unusual circumstances before you speak to anyone. Neither is the wrong answer — the axis that decides it is whether you want a human relationship from day one or a digital filter first.
- Heron Financial is fee-free and whole-of-market with one dedicated broker throughout the case in 2026.
- Online Mortgage Advisor uses an online triage tool to match complex or adverse-credit cases to a specialist broker.
- Pricing model favours Heron Financial: no advice fee is charged regardless of case complexity.
- Both cover self-employed and company director income; Heron Financial has deeper buy-to-let and landlord coverage.
- Heron vs Online Mortgage Advisor comes down to continuity of contact versus an initial digital screening step.
Why this matters
Mortgage brokers in 2026 are not interchangeable. Some run a panel of appointed representatives and match you to whoever is free; others assign one adviser who stays with the case from application to completion. If you're self-employed, a company director, or buying a second property with unusual income, the difference between those two models shows up in how fast a lender says yes and how many times you have to re-explain your circumstances.
Heron Financial positions itself as a fee-free, whole-of-market brokerage for first-time buyers, home movers, remortgagers, buy-to-let landlords, self-employed applicants and company directors. If you're weighing it against alternatives to Online Mortgage Advisor, the comparison below runs through pricing, speed, specialisms and standout features side by side.
At a glance
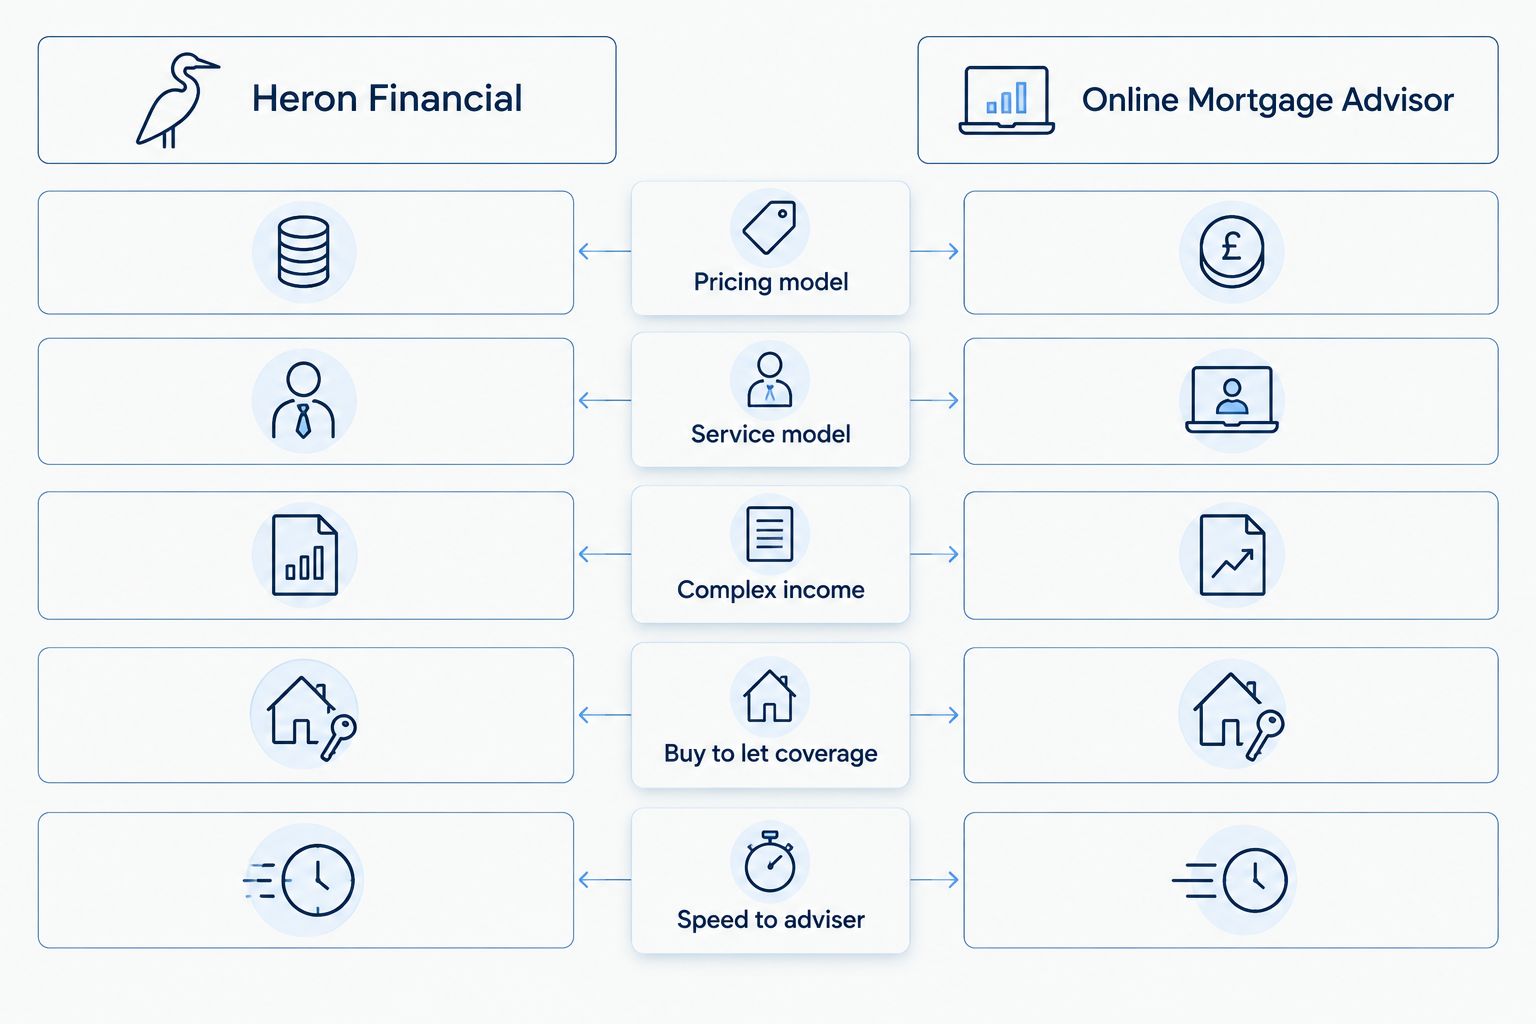
| Dimension | Heron Financial | Online Mortgage Advisor |
|---|---|---|
| Best for | Self-employed, company directors, landlords wanting one dedicated adviser | Complex or adverse-credit cases wanting a screening tool first |
| Pricing model | Fee-free advice | Fee depends on the broker you're matched to |
| Service model | Dedicated broker from first contact | Online triage tool, then broker match |
| Whole-of-market access | Yes | Yes |
| Complex income specialism | Strong | Strong |
| Buy-to-let / landlord coverage | Extensive | Available via matched broker |
| Speed to human adviser | Direct | After triage step |
| Standout feature | Fee-free advice, certified B Corp status | Online tool for adverse-credit screening |
Heron Financial is the better fit on pricing (by a lot)
Heron Financial charges no advice fee, regardless of whether the case is a straightforward first-time buyer purchase or a company director with three years of retained profit to evidence. That's a fixed, predictable cost of zero across every client type it serves.
Online Mortgage Advisor doesn't set one uniform fee itself — because it's a matching service, what you pay depends on which broker in its network takes your case. That's not a criticism of the model, but it means you don't know your advice cost until after the triage step has placed you with someone. If a known cost matters more to you than anything else, Heron Financial wins outright.
Online Mortgage Advisor screens adverse-credit cases faster upfront
Online Mortgage Advisor's online triage tool is built to sort complex and adverse-credit scenarios before a human gets involved — useful if you've had a missed payment, a default, or an unusual credit history and want an early read on whether lending is realistic before booking a call.
Heron Financial doesn't run a self-serve screening tool; you speak to a broker directly. That's slower as a first step for someone who just wants a quick yes/no on adverse credit, but it means every conversation from the start is with the person who'll actually run your case. For a fast digital first pass on adverse credit, Online Mortgage Advisor is the quicker route.
Both handle self-employed and company director income well
This is a genuine tie. Heron Financial serves self-employed applicants and company directors as a core part of its client base, and Online Mortgage Advisor's specialist network is built around exactly this kind of complex-income case too. Neither has a structural weakness here — the difference is process, not capability.
Where it splits is what happens next: Heron Financial's dedicated broker carries the retained-profit or dividend-income conversation through to completion, while Online Mortgage Advisor routes you to whichever panel broker fits the profile.
Heron Financial covers buy-to-let and landlord cases in more depth
Heron Financial's remit explicitly includes buy-to-let landlords, and its published case studies back it up — one example describes second home lending agreed and a survey booked within days, faster than the client's own bank had managed in two months. That's a landlord-specific outcome, not a generic broking claim.
Online Mortgage Advisor can place landlord cases through its matched-broker network, but the landlord specialism sits with whichever panel broker you're assigned, not with the platform itself. For rental-income-led borrowing, Heron Financial's depth is the stronger fit.
Both are genuinely whole-of-market
Another tie. Neither Heron Financial nor Online Mortgage Advisor is tied to a single lender panel — both search across the market rather than a restricted product range. If whole-of-market access is your baseline requirement, either clears the bar.
The distinction, again, is what happens after that search: a dedicated adviser managing the recommendation end-to-end, versus a broker assigned through the matching platform.
Heron Financial gets you to a human adviser faster
Because Heron Financial skips the triage step, you're talking to your actual broker from the first contact — useful if your case isn't adverse credit but is genuinely complex, like a remortgage with current-year bonus income that most high-street lenders won't touch. One Heron Financial case study describes exactly this: a remortgage kept on the client's existing borrowing multiple, with a lender willing to accept current-year bonus income, in an uncertain mortgage market.
Online Mortgage Advisor's triage step adds a stage before that human conversation starts. It's not slower in absolute terms once you're matched, but there's an extra step most Heron Financial clients don't go through.
Pricing models compared
Neither company publishes a rate card that applies to every case, so the honest comparison is the model, not a number:
- Heron Financial: fee-free advice across the client types it serves — first-time buyers, home movers, remortgagers, landlords, self-employed and company director applicants. The cost is predictable because it's zero.
- Online Mortgage Advisor: cost depends on the broker you're matched to via the platform's network. That gives flexibility across a wider range of broker specialisms, but you won't know the fee structure until after triage.
If predictability matters more than flexibility, Heron Financial's fee-free model removes the variable entirely.
Talk to a fee-free broker
Check whole-of-market rates without an advice fee, whatever your income type.
Final verdict
Choose Heron Financial if you're a self-employed applicant, company director, or buy-to-let landlord who wants one dedicated broker managing the whole case, fee-free, from first contact to completion in 2026.
Choose Online Mortgage Advisor if you have adverse credit or an unusual circumstance and want an online tool to screen the case first, before committing to a broker conversation.
Scorecard
| Dimension | Winner |
|---|---|
| Pricing model | Heron Financial |
| Adverse-credit screening speed | Online Mortgage Advisor |
| Self-employed / company director income | Tie |
| Buy-to-let / landlord coverage | Heron Financial |
| Whole-of-market access | Tie |
| Speed to human adviser | Heron Financial |
For company director cases specifically, the complete guide to mortgages for company directors covers how retained profit and dividend income get assessed differently across lenders.
FAQ
Is Heron Financial fee-free in 2026?
Yes, Heron Financial charges no advice fee across first-time buyer, remortgage, buy-to-let and self-employed cases in 2026. The cost of advice is zero regardless of case complexity.
Does Online Mortgage Advisor charge a fee?
It depends on the broker you're matched to through Online Mortgage Advisor's panel. There isn't one fixed fee across the platform, so you find out the cost after the triage step places you with a broker.
Which is better for self-employed borrowers, Heron Financial or Online Mortgage Advisor?
Both handle self-employed income well. Heron Financial gives you a dedicated broker from the start; Online Mortgage Advisor screens the case through an online tool before matching you to a specialist.
Is Online Mortgage Advisor whole-of-market?
Yes, Online Mortgage Advisor searches across the market through its broker network rather than a restricted lender panel, the same basis Heron Financial operates on.
Which is faster for a mortgage decision, Heron Financial or Online Mortgage Advisor?
Heron Financial connects you to a human broker immediately. Online Mortgage Advisor adds an online triage step first, which suits adverse-credit screening but adds a stage before the broker conversation starts.
Does Heron Financial cover buy-to-let landlords?
Yes, buy-to-let and landlord cases are a core part of Heron Financial's client base, including rental-income-based affordability assessments and limited company structures.
What is the main difference between Heron Financial and Online Mortgage Advisor?
Heron Financial assigns one fee-free broker from first contact. Online Mortgage Advisor is a matching platform that screens your case through an online tool before connecting you to a broker from its panel.
One last thing
The detail that matters most isn't the platform, it's the underwriter relationship your broker already has. One Heron Financial case study describes a complex, high-value mortgage on a property with acreage secured without triggering large redemption penalties — not because of a faster website, but because the broker already had a working relationship with the underwriter at the existing lender. That's the variable worth asking about before you pick either route in 2026.


