
Heron Financial is the right call if you want direct, fee-free, whole-of-market mortgage advice from one broker who stays with your case start to finish. Unbiased is the right call if you want to browse a directory of independent financial advisers — including mortgage specialists — and pick one yourself after comparing profiles. The axis of difference is simple: one is a broker, the other is a matching platform that hands you off to a broker.
- Heron Financial vs Unbiased comes down to broker vs directory: one advises you directly, the other matches you to someone who will.
- Heron Financial is fee-free and whole-of-market for mortgages and protection across the UK in 2026.
- Unbiased lists advisers across mortgages, pensions, investments and tax — not mortgages exclusively.
- Self-employed applicants and company directors get a broker built around complex income with Heron Financial.
- Both routes only put you in front of FCA-regulated advisers.
Why this matters
Mortgage criteria in 2026 are tighter around variable income, and lenders differ wildly on how they treat bonus income, dividends, or a company director's retained profit. Picking the wrong route wastes weeks. A broker who takes your case on directly, like Heron Financial, can start work the same day. A directory adds a step: you still have to find, vet and brief an adviser before any lender conversation begins.
That extra step isn't always wasted time — if you want to compare adviser philosophies, fee structures or specialisms before committing, a directory earns its place. But if your priority is speed and a single point of accountability, the directory model works against you.
At a glance
| Dimension | Heron Financial | Unbiased |
|---|---|---|
| What it is | Fee-free, whole-of-market mortgage and protection broker | Directory matching consumers with independent financial advisers |
| Best for | Direct advice with complex or variable income | Comparing multiple advisers before choosing one |
| Pricing model | Fee-free to the client | Matched adviser sets their own fee structure |
| Speed to advice | Advice starts from first contact | Search, shortlist, contact each adviser separately |
| Self-employed / company director expertise | Built around complex income cases | Depends entirely on the adviser matched |
| Whole-of-market mortgage access | Standard on every case | Depends on the matched adviser's panel |
| Advice scope | Mortgages and protection insurance | Mortgages, pensions, investments, tax, later-life planning |
| Ongoing relationship | Single broker across purchase, remortgage and protection | New search needed if the matched adviser isn't a fit |
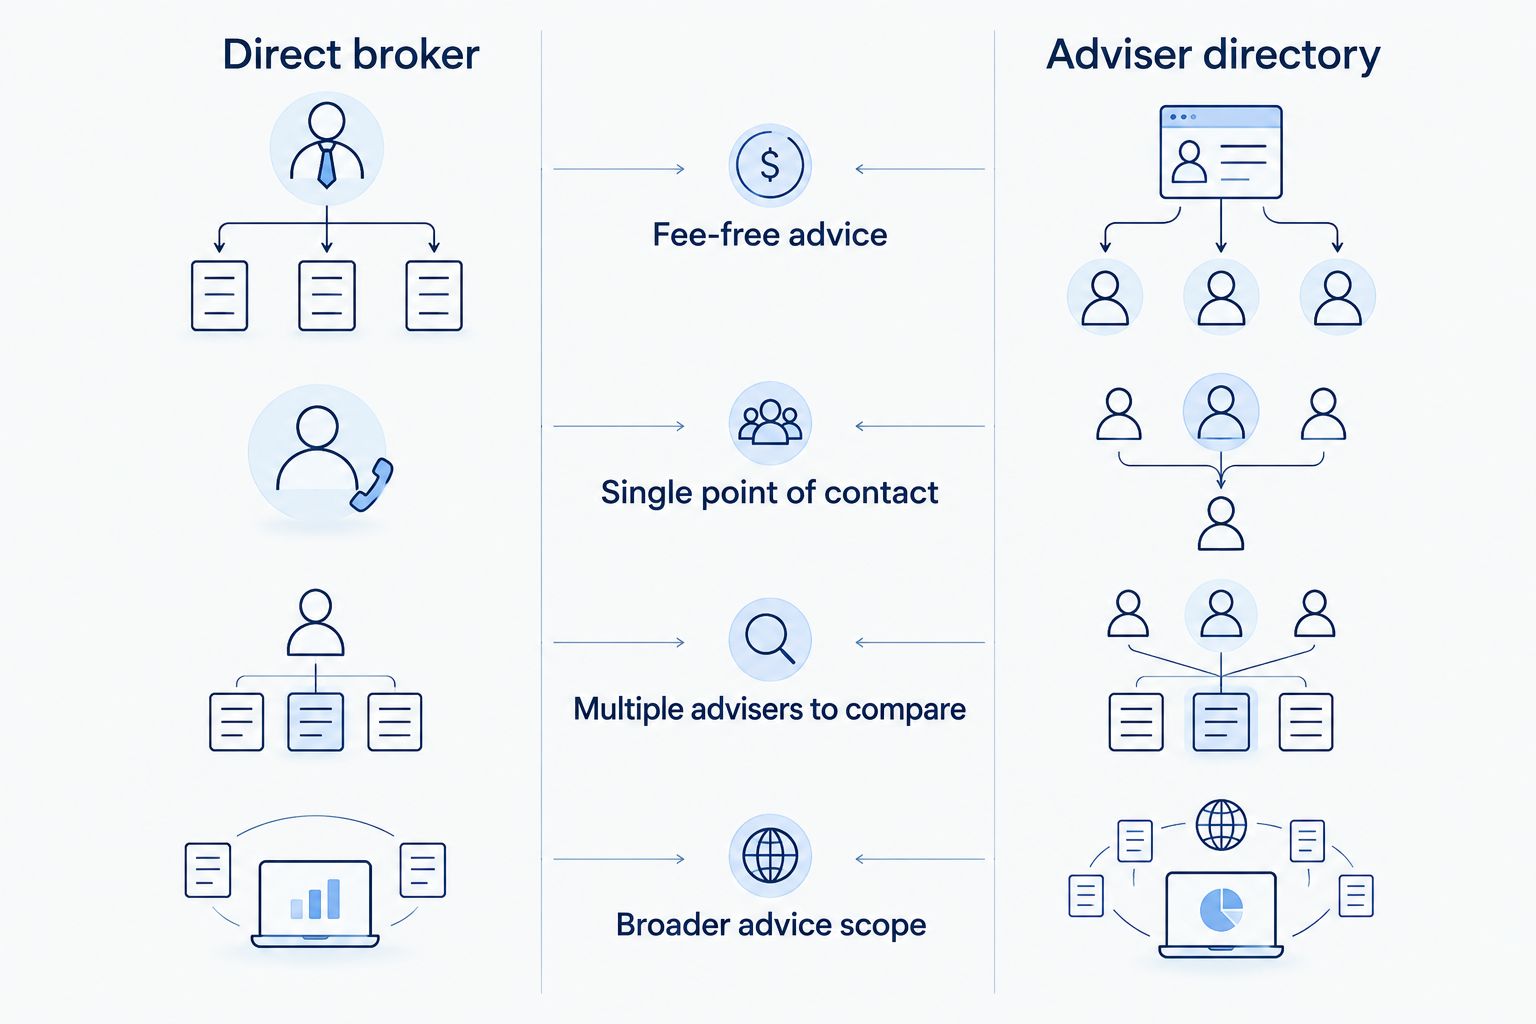
Heron Financial gets you talking to a broker immediately
With Heron Financial, the first conversation is with the person who will actually work your case, not a triage step before a hand-off. That matters for time-sensitive purchases and for remortgages against a redemption penalty deadline.
Unbiased requires you to search adviser profiles, shortlist a few, and contact each one before any mortgage-specific conversation starts. Heron Financial wins on speed to first advice, clearly.
Heron Financial specialises in complex and variable income
Heron Financial's case base runs through first-time buyers, home movers, remortgagers, buy-to-let landlords, self-employed applicants and company directors — income types lenders assess inconsistently. That specialism shapes which lenders get approached first for a case with dividend income or a short trading history.
Unbiased doesn't specialise in anything itself — it's a directory. The adviser you're matched with might have deep company director experience, or might not. Heron Financial wins on complex-income depth because that depth is built in, not a matter of luck in matching. If your income is self-employed, self-employed borrowers face lender-by-lender variation that a specialist broker tracks daily.
Whole-of-market access is guaranteed with Heron Financial, not with Unbiased
Heron Financial is whole-of-market as standard — every case gets screened against the full lending panel, not a restricted shortlist. That's a structural fact of how the brokerage operates, not a claim tied to any one adviser.
With Unbiased, whole-of-market access depends entirely on which adviser you're matched with. Some independent advisers are whole-of-market; others work from a narrower panel. Heron Financial wins here because the guarantee doesn't shift by adviser.
Both only put you in front of FCA-regulated advice
Heron Financial operates as an Appointed Representative under FCA regulation. Unbiased only lists advisers who are themselves FCA-regulated. This one's a genuine tie — regulatory protection is equivalent either way, so it shouldn't be the deciding factor between them.
Unbiased covers more than mortgages
If you need a mortgage adviser and a pensions adviser and someone for inheritance tax planning, Unbiased's directory spans all of that in one search. Heron Financial's remit is mortgages and protection insurance — it doesn't advise on pensions, investments or general wealth planning.
Unbiased wins on breadth of advice scope if your need extends past mortgages and protection into wider financial planning.
Unbiased wins if you want to compare adviser profiles first
Some borrowers want to read a few adviser bios, check specialisms and fee models, and choose deliberately before the first call. That's exactly what a directory is built for.
Unbiased wins on choice and comparison for anyone who values that browsing step over speed. Heron Financial doesn't offer that browsing layer — you're speaking to one named brokerage from the start.
Pricing: fee-free versus adviser-set fees
Heron Financial's mortgage and protection advice is fee-free to the client — the model is built around not charging borrowers directly. That's predictable: you know the cost structure before you start.
Unbiased itself doesn't set fees; the adviser you're matched with does, and fee models vary from adviser to adviser, from fixed fees to percentage-based charges depending on the firm. That's the flexibility-versus-predictability trade-off in plain terms: Heron Financial's model removes the fee question entirely, Unbiased's model means the fee question depends on who you're matched with.
Talk to a broker directly
Fee-free whole-of-market mortgage advice, no directory search required.
Final verdict
Choose Heron Financial if: you're a self-employed applicant, company director, landlord or remortgager who wants one fee-free broker handling the whole case, with whole-of-market access guaranteed rather than dependent on who you're matched with. A company director remortgaging against a tightening lending market fits this profile exactly — see the company director mortgage guide for how lenders treat retained profit and dividends.
Choose Unbiased if: you want a broader financial planning relationship covering mortgages alongside pensions, investments or tax, and you'd rather compare several adviser profiles before committing to one. Someone consolidating a mortgage search with a wider wealth review fits this profile. For a direct comparison of what a directory search actually surfaces versus a dedicated broker, the Unbiased alternatives for finding a mortgage broker breakdown covers the trade-offs in more depth.
Scorecard recap
| Dimension | Winner |
|---|---|
| Speed to first advice | Heron Financial |
| Complex/self-employed income expertise | Heron Financial |
| Whole-of-market guarantee | Heron Financial |
| FCA regulation | Tie |
| Breadth of advice scope | Unbiased |
| Adviser choice and comparison | Unbiased |
FAQ
Is Heron Financial better than Unbiased for mortgages?
For a direct, fee-free, whole-of-market mortgage broker relationship, Heron Financial is the stronger fit in 2026. Unbiased is better suited to borrowers who want to compare several independent advisers before committing.
Does Unbiased charge a fee?
Unbiased itself is a matching directory; the adviser you're matched with sets their own fee structure, which varies by firm. There's no single fee model across every adviser listed.
Is Heron Financial fee-free?
Yes, Heron Financial provides mortgage and protection advice on a fee-free basis to the client. That's built into how the brokerage operates, not a promotional offer.
What's the difference between a mortgage broker and Unbiased?
A mortgage broker like Heron Financial advises you directly and searches the lending panel on your behalf. Unbiased is a directory that matches you with an independent adviser, who then provides the actual advice.
Can I use Unbiased for a company director mortgage?
You can be matched with an adviser through Unbiased who handles company director cases, but the depth of that specialism depends entirely on which adviser you're matched with.
Is Heron Financial whole-of-market?
Yes, Heron Financial screens every case against the full lending panel as standard, rather than a restricted or preferred list.
Which is faster, Heron Financial or Unbiased?
Heron Financial is faster to first advice because you speak directly with the broker working your case. Unbiased adds a search and shortlisting step before any mortgage-specific conversation starts.
One last thing
The detail borrowers miss most in 2026: a directory match isn't a guarantee of whole-of-market access — it's a guarantee of FCA regulation, which is a different thing entirely. If whole-of-market coverage matters to your case, confirm it directly with whichever adviser a directory hands you, rather than assuming it.


