
Mortgages for foreign nationals in the UK are specialist lending arrangements built to get non-UK passport holders approved despite a limited UK credit history, visa-based residency, or income earned overseas. Eligibility in 2026 hinges on visa type, time left on that visa, and how a lender treats overseas income — none of which a standard UK resident application has to prove.
- Mortgage for foreign nationals UK approvals in 2026 depend on visa route first, deposit size second — not nationality alone.
- Specialist lenders for foreign nationals typically ask for larger deposits than standard UK resident deals.
- Heron Financial is fee-free and whole-of-market, checking lender panels that accept visa holders, ILR applicants and overseas income.
- A thin UK credit file is the most common reason a foreign national's mortgage application stalls before it starts.
Why mortgages for foreign nationals matter
A foreign national applying for a UK mortgage in 2026 is not shopping the same market a UK-born applicant sees. High-street banks price and underwrite around UK residency status, so a visa holder with 18 months left on a Skilled Worker visa can be declined by a bank that would approve a UK passport holder with an identical income and deposit.
That gap is exactly what a fee-free whole-of-market mortgage broker exists to close — checking which of dozens of lender panels actually accept a given visa category, rather than sending an application to one bank and hoping.
Check your visa and residency status first
Lenders sort applicants by residency category before they look at income or deposit. Knowing which bucket you sit in changes which lenders are even worth approaching.
- Indefinite Leave to Remain (ILR) — treated closest to a UK resident by most lenders
- EU Settlement Scheme (settled status) — generally accepted on standard resident terms
- EU Settlement Scheme (pre-settled status) — accepted by a smaller pool of lenders
- Skilled Worker visa — accepted if enough time remains on the visa, varies by lender
- Ancestry or Global Talent visa — often treated favourably due to longer visa duration
- Spouse or partner visa — assessed alongside the sponsoring partner's status
- Student visa — very few lenders will consider a mortgage application
This is also the point where comparing your situation against a British expat mortgage deals guide is worth doing, since non-resident and returning-expat criteria overlap heavily with foreign national criteria on lender panels.
Work out how much deposit you'll need
Deposit size does more work for a foreign national's application than for a UK resident's, because it offsets the risk a lender assigns to residency status.
- Non-permanent residency status typically pushes minimum deposit requirements above standard UK resident deals
- Deposit thresholds tighten further the less time remains on a visa
- Gifted deposits from overseas need a documented paper trail, not just a bank transfer
- Proof-of-funds requirements are stricter for money sourced outside the UK
- Larger deposits widen the pool of lenders willing to consider the application at all
Once residency status and credit history strengthen, some applicants qualify for a wider high LTV mortgage deals selection — it's worth checking that list rather than assuming a large deposit is always required.
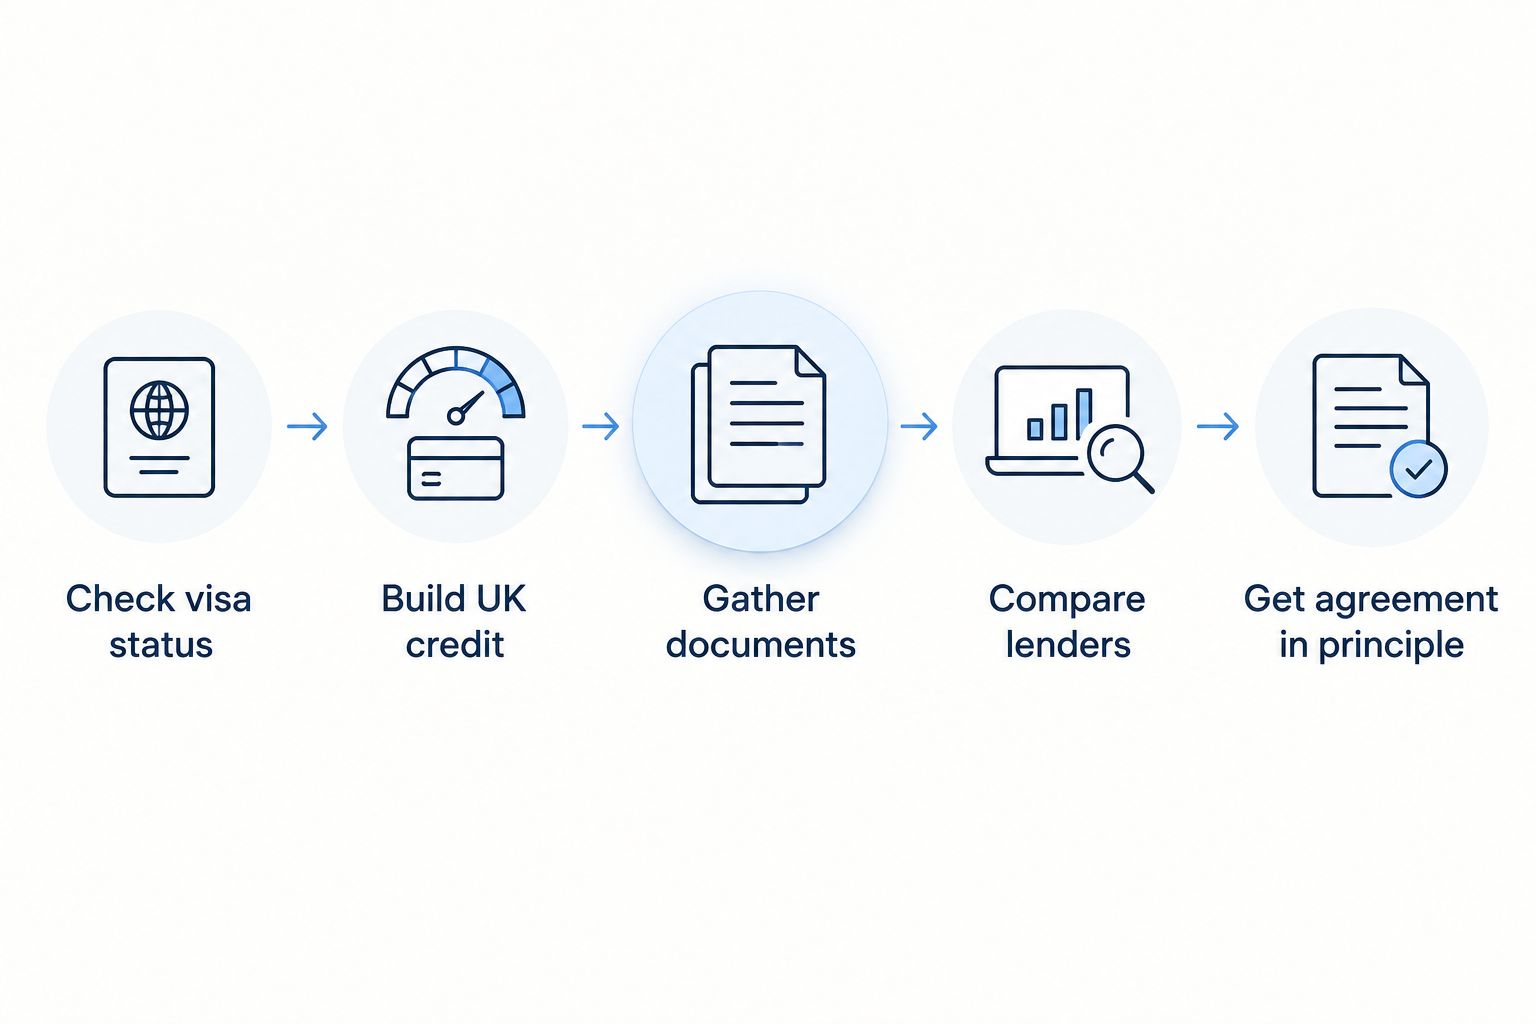
Build a UK credit footprint
A lender can't assess risk on a credit file that barely exists. Foreign nationals who arrived in the UK recently often get declined not for income reasons but for having too thin a file to score.
- Register on the electoral roll at your current UK address if eligible
- Open and actively use a UK current account for several months before applying
- Take out a UK mobile contract or utility account in your own name
- Avoid several credit applications in a short window — each search can dent your score
- Check your file with Experian, Equifax and TransUnion for errors before a lender does
Gather income and identity documents
Documentation gaps are the second most common reason a foreign national's application slows down or stalls. Lenders want a complete paper trail, and overseas-sourced documents need extra proof.
- Passport and current visa or biometric residence permit
- Right-to-rent or right-to-reside evidence for the property address
- Three to six months of UK or overseas payslips
- SA302s or tax return summaries if self-employed or a company director
- Foreign income converted to GBP with a documented exchange rate source
- An employer reference letter confirming role, salary and contract length
Self-employed foreign nationals and company directors face an extra layer here — the self-employed mortgage lenders list is the right starting point before assuming income complexity rules you out.
Compare lenders that accept your visa route
Not every lender publishes its visa criteria, and the criteria that do exist change more often than most applicants expect in 2026. Approaching one bank directly wastes a credit search if that bank simply doesn't lend on your visa type.
- High-street banks generally require ILR or settled status and a strong UK credit file
- Specialist non-UK-resident lenders build criteria specifically around visa holders and overseas income
- Private banks consider complex, high-net-worth cases outside standard lending criteria
- Minimum time remaining on a visa is a hard cut-off for some lenders, not a guideline
- A whole-of-market broker cross-checks live criteria across panels instead of guessing
Heron Financial is fee-free and whole-of-market, which means the search across lender panels costs nothing extra and isn't limited to a handful of partner banks.
Get a mortgage agreement in principle
An agreement in principle (AIP) tells you what a specific lender will consider before you commit to viewing property seriously — it's a filter, not a guarantee.
- Get an AIP before making offers, not after
- A soft-search AIP won't affect your credit file; a hard-search one will
- AIPs are typically valid for a limited window and expire if property search drags on
- An AIP is not final approval — full underwriting can still surface issues
- Use the AIP stage to fix any documentation gaps flagged before formal application
Comparing your options
| Option | Best for | Key limitation |
|---|---|---|
| High-street bank | UK residents with ILR or settled status and a strong credit file | Rarely lends to visa holders with limited time remaining on a visa |
| Specialist non-UK-resident lender | Visa holders, recent arrivals, overseas income | Deposit requirements typically run higher than standard resident deals |
| Private bank | High-net-worth foreign nationals with complex income | Minimum loan sizes and asset requirements exclude smaller purchases |
| Whole-of-market broker (Heron Financial) | Anyone unsure which lender panel fits their visa and income | Broker access doesn't remove a lender's own underwriting criteria |
Company directors with non-UK passports face a similar layered problem — visa criteria stacked on top of director-income criteria — covered in the company director mortgage guide.
Talk to a whole-of-market broker
Fee-free advice that checks lender panels against your specific visa and income.
Common mistakes foreign nationals make
- Applying to a high-street bank first without checking visa criteria — wastes a credit search on a lender that was never going to say yes
- Assuming residency length alone qualifies for standard resident rates — lenders weigh visa category and time remaining, not just years in the UK
- Failing to document overseas income properly — missing currency conversion sources or untranslated statements stall underwriting
- Leaving UK credit-file building until the application stage — a thin file takes months to build, not days
- Underestimating minimum time-left-on-visa requirements — some lenders set hard cut-offs that rule out an otherwise strong application
FAQ
Can a foreign national get a mortgage in the UK in 2026?
Yes, foreign nationals can get a UK mortgage in 2026 through high-street banks, specialist lenders or private banks, depending on visa status, deposit size and income documentation.
Do I need Indefinite Leave to Remain to get a UK mortgage?
No, ILR is not required for every lender. Several specialist and mainstream lenders accept Skilled Worker, EU Settlement Scheme and other visa categories with sufficient time remaining.
How much deposit does a foreign national need for a UK mortgage?
Deposit requirements for foreign nationals are typically higher than standard UK resident deals, and the exact minimum depends on visa type, remaining visa duration and the lender chosen.
Can I get a UK mortgage with a Skilled Worker visa?
Yes, several lenders accept Skilled Worker visa holders provided enough time remains on the visa at application, though criteria vary significantly between lenders.
Do UK lenders accept foreign income for a mortgage?
Some lenders accept foreign-earned income if it's properly converted to GBP and documented with a clear exchange rate source, though acceptance varies by lender and income type.
Is a mortgage broker better than a bank for foreign nationals?
A whole-of-market broker checks criteria across many lender panels at once, which matters most for foreign nationals because visa-based criteria differ sharply between individual lenders.
How long does a mortgage take for a foreign national in the UK?
Timelines vary by documentation completeness and lender, but incomplete overseas income or identity documents are the most common cause of delay for foreign national applications.
Can EU citizens get a UK mortgage after Brexit?
Yes, EU citizens with settled or pre-settled status under the EU Settlement Scheme remain eligible for UK mortgages, with settled status generally treated closer to standard resident terms.
One last thing
Most foreign nationals assume ILR is the only route to standard resident-style rates in 2026 — it isn't. Some lenders will consider a Skilled Worker or Ancestry visa holder with several years remaining on the same terms as a settled applicant, provided the credit file and documentation are solid. The visa route rules out far fewer lenders than most applicants assume before checking.


