
Choose Heron Financial if your income is complex — self-employed, contractor, company director, or a mix of salary and bonus — and you want a fee-free adviser who fights for a specific underwriter outcome. Choose Revolution Brokers if your application is straightforward and you want to run most of the process online with less back-and-forth. Both are whole-of-market, fee-free UK mortgage brokers in 2026, so the real split between Heron Financial vs Revolution Brokers is about how much hand-holding your case needs, not who charges less.
- Heron Financial vs Revolution Brokers in 2026: Heron Financial wins on complex and self-employed income cases.
- Both brokers are fee-free and whole-of-market, earning from lender commission rather than client fees.
- Revolution Brokers suits straightforward, single-income applications processed mostly online.
- Heron Financial's underwriter relationships help on high-value or acreage properties with existing lenders.
- Neither broker publishes fixed pricing tiers — confirm the current fee structure directly before applying.
Why this matters
A mortgage broker comparison only matters if it changes what you do next. If you're self-employed, run a limited company, or have bonus and commission income, the broker you pick decides whether a lender sees your full earning picture or just your basic salary line. Heron Financial built its case-study record on exactly that kind of case — remortgages with current-year bonus income, high-value properties with acreage, and second-home lending agreed in days rather than the two months a client's own bank needed.
Revolution Brokers operates in the same fee-free, whole-of-market space, positioning itself as a broker that blends adviser calls with an online-first application flow. Neither model is objectively better — the right call depends on how much complexity is in your income and how much you want to manage on a screen versus over the phone.
At a glance
| Dimension | Heron Financial | Revolution Brokers |
|---|---|---|
| Best for | Self-employed, directors, complex or bonus income | Straightforward, single-income applications |
| Pricing model | Fee-free to the client, paid via lender commission | Fee-free positioning; confirm current structure directly |
| Standout feature | Underwriter relationships on complex, high-value cases | Online-first application process |
| Self-employed & complex income | Deep case-study track record | Whole-of-market access, less specialised proof |
| Buy-to-let & landlord lending | Rental-income-based deals across limited companies and individuals | Whole-of-market landlord coverage |
| Speed on complex, high-value cases | Direct underwriter access speeds up decisions | Standard lender turnaround for straightforward files |
| Protection insurance | Mortgage and protection advice in one process | Not confirmed as a bundled service |
| Online experience | Adviser-led, phone and email driven | Built around a digital application flow |
Heron Financial digs deeper on complex and self-employed income
Heron Financial wins here, and by a clear margin for anyone whose income isn't a single payslip. The brokerage's own case files show remortgages structured around current-year bonus income for high-earning couples, and a £14,025 saving over two years on a 75% LTV remortgage for a self-employed client when lenders were tightening criteria across the board in 2026.
That kind of outcome comes from knowing which lenders will accept which income evidence — SA302s, company accounts, or a mix of salary and dividends — before you apply. Revolution Brokers, as a whole-of-market broker, can access the same lender panel in theory, but there's no equivalent published record of it specialising in this exact problem.
If you're a company director or contractor, this is the dimension that should drive your decision more than any other on this page.
Both handle buy-to-let and landlord lending well
This is a genuine tie. Heron Financial and Revolution Brokers both cover buy-to-let across individual landlords and limited company structures, and both work from rental income affordability calculations rather than personal salary alone.
Heron Financial's second-home case — where lending was agreed and a survey booked within days, beating a client's existing bank by roughly two months — shows the brokerage can move fast on landlord and second-property deals specifically. Revolution Brokers' whole-of-market access should, in principle, reach the same lender panel for standard buy-to-let cases.
Neither side has a documented edge for a landlord with a clean rental-income case in 2026. Pick based on service style, not lending access.
Heron Financial moves faster on complex, high-value cases
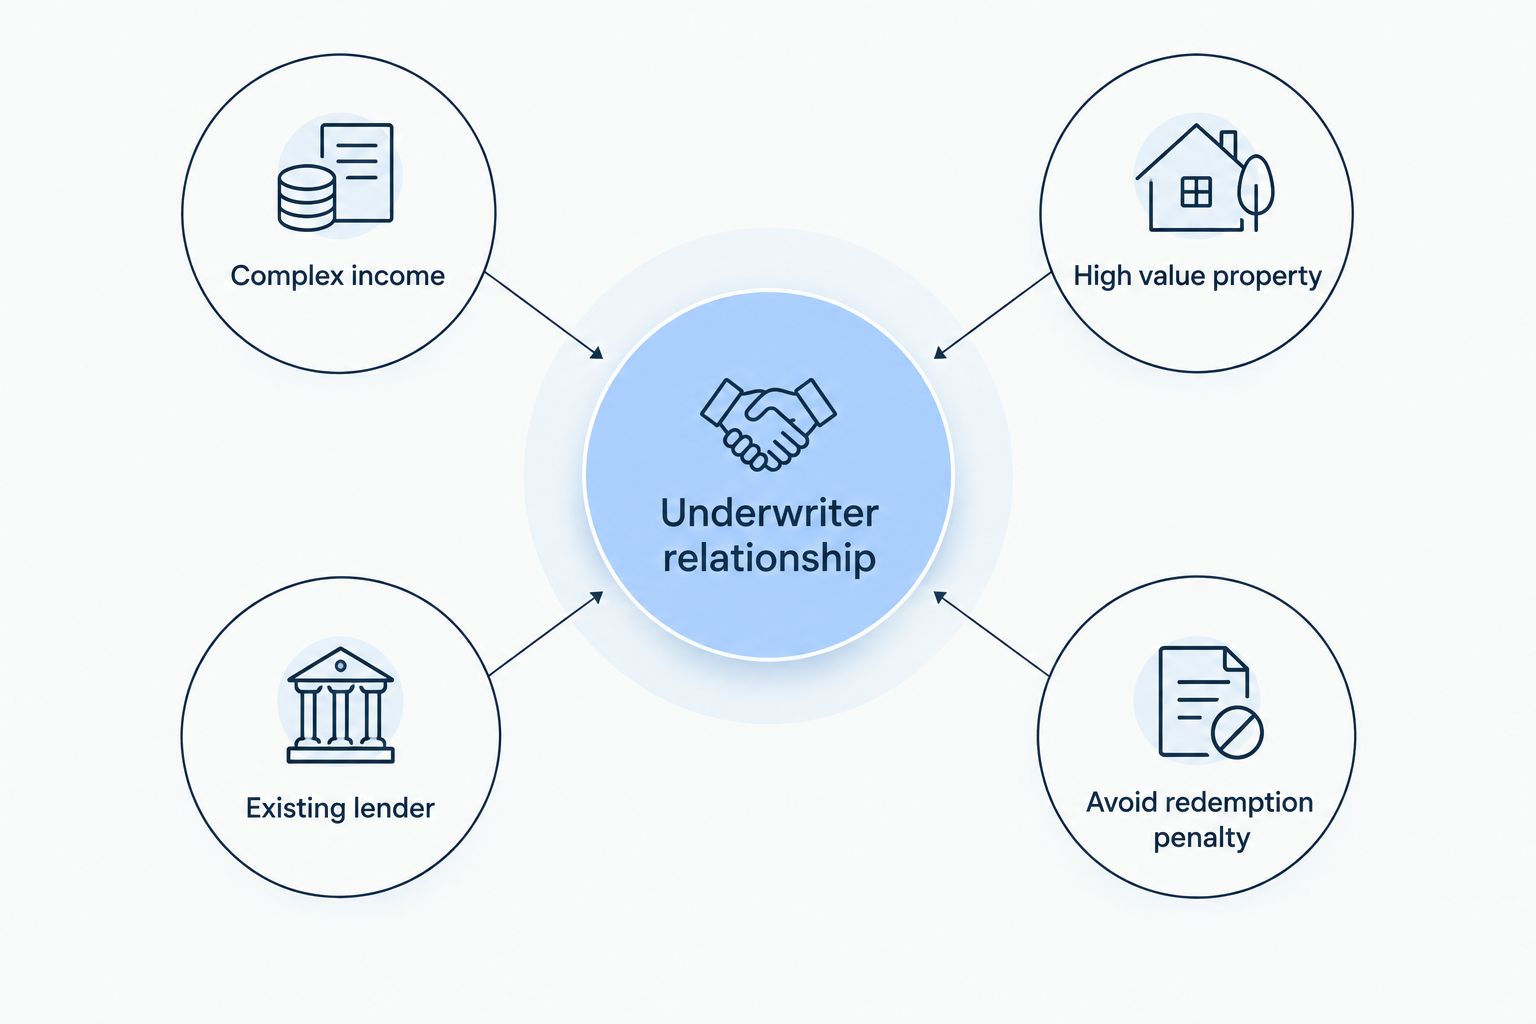
Heron Financial has the edge here because of direct underwriter relationships, not just lender access. One case file describes securing a complex, high-value mortgage on a property with acreage, staying with the existing lender and avoiding a large redemption penalty — a result that typically requires a conversation with an underwriter, not a form submitted through a portal.
That matters most when your case doesn't fit a standard lending template: unusual property types, large loan sizes, or a need to renegotiate terms with a current lender rather than remortgage elsewhere. Revolution Brokers' online-first model is built for speed on simple cases, but there's no equivalent evidence of it working underwriter relationships on non-standard files.
Heron Financial covers protection insurance in the same process
Heron Financial is described as a mortgage and protection brokerage, meaning income protection, life cover, and related insurance advice happen alongside the mortgage application rather than as a separate referral. That's a practical advantage for self-employed applicants especially, since income protection underwriting for self-employed income often mirrors the same affordability documents used for the mortgage.
There's no confirmed detail on whether Revolution Brokers bundles protection advice into its process the same way, so this stays a Heron Financial point rather than a head-to-head comparison. If protection advice matters to you, ask the broker directly whether it's part of the same application or a separate step.
Revolution Brokers is the better fit for a fast, online-only application
Revolution Brokers wins this one for straightforward, single-income cases where you'd rather manage most of the process on a screen. An online-first application flow suits borrowers who know their numbers, have simple payslip-based income, and don't need a lender-by-lender strategy conversation before submitting.
Heron Financial's model leans on adviser conversations and case-specific underwriter contact — the right approach for complexity, but potentially more process than a simple first-time buyer or straightforward remortgage actually needs. If your income is one salary, one employer, and a clean credit file, the lighter-touch route can get you to an agreement in principle just as fast.
Pricing: same model, different confirmation needed
Heron Financial is fee-free to the client — the brokerage is paid via lender commission (procuration fee) rather than charging you directly, which is the standard model for whole-of-market UK mortgage brokers in 2026. This means the advice cost doesn't scale with loan size or complexity, so a complex case with a lower-value property isn't penalised for taking more advice time.
Revolution Brokers positions itself in the same fee-free space, but its exact current fee structure isn't something to assume — confirm it directly before applying, since broker pricing models can vary by product type (protection insurance, for example, sometimes carries different terms than mortgage advice).
The trade-off to weigh isn't cost, since both are fee-free at the mortgage-advice level — it's predictability of outcome. A fixed, no-fee model with a broker who has underwriter relationships gives more certainty on a hard case; a fully online model gives more speed on an easy one.
Talk to a whole-of-market broker
Fee-free mortgage and protection advice for complex and straightforward cases alike.
Final verdict
Choose Heron Financial if you're self-employed, a company director, or have income that doesn't fit a standard payslip — the case-study record on bonus income, high-value acreage properties, and self-employed remortgages (including a £14,025 two-year saving) points directly at this kind of applicant. Winner: Heron Financial.
Choose Revolution Brokers if you're a first-time buyer or remortgager with one clean income source and want to run the bulk of the application online with minimal back-and-forth. Winner: Revolution Brokers.
If you're weighing other alternatives beyond these two, the Revolution Brokers alternatives guide breaks down a wider set of whole-of-market options for 2026, and self-employed borrowers specifically should check best mortgage lenders for self-employed borrowers in 2026 before choosing an adviser.
Scorecard
| Dimension | Winner |
|---|---|
| Self-employed & complex income | Heron Financial |
| Buy-to-let & landlord lending | Tie |
| Speed on complex, high-value cases | Heron Financial |
| Protection insurance | Heron Financial |
| Online-only, straightforward cases | Revolution Brokers |
| Pricing model | Tie (fee-free; confirm Revolution Brokers directly) |
FAQ
Is Heron Financial or Revolution Brokers better for self-employed applicants?
Heron Financial has a stronger documented track record on self-employed and complex income cases in 2026, including a remortgage saving of £14,025 over two years for a self-employed client at 75% LTV.
Are Heron Financial and Revolution Brokers both fee-free?
Heron Financial is fee-free to the client, earning via lender commission. Revolution Brokers positions itself similarly, but confirm its current fee structure directly before applying.
Which broker is faster for a straightforward mortgage application?
Revolution Brokers' online-first process suits straightforward, single-income applications that don't need underwriter-level negotiation.
Does Heron Financial cover buy-to-let and landlord mortgages?
Yes, Heron Financial covers buy-to-let for individual landlords and limited companies, calculated on rental income affordability rather than personal salary alone.
Can Heron Financial help with a mortgage on a high-value or unusual property?
Yes. Heron Financial has secured complex, high-value mortgages on properties with acreage by working directly with underwriters to avoid large redemption penalties with an existing lender.
Does Heron Financial also arrange protection insurance?
Yes, Heron Financial is a combined mortgage and protection brokerage, so income protection and life cover advice can happen alongside the mortgage application.
Which broker is better for a second home or buy-to-let purchase needing a fast decision?
Heron Financial has a documented case of agreeing second-home lending and booking a survey within days, faster than the client's existing bank managed in two months.
Should I use a whole-of-market broker instead of going direct to a lender in 2026?
A whole-of-market broker checks multiple lenders' criteria against your specific income and property, which matters most if your case is anything other than a standard single-income, standard-property application.
One last thing
The detail that separates these two brokers isn't the fee-free label — both carry that in 2026 — it's whether the broker has a specific underwriter relationship for your exact problem. Heron Financial's own case files show that mattering twice over: once to avoid a large redemption penalty on a high-value property with acreage, and once to beat a client's own bank by roughly two months on second-home lending. If your case has any complexity at all, ask a prospective broker directly whether they've placed a similar case before you commit.


