
A high-net-worth mortgage is a lending arrangement built around total wealth and complex income rather than a single payslip, with the aim of securing large loan amounts and competitive terms that standard affordability calculators cannot process. Borrowers in this segment usually hold income from dividends, trusts, business equity or investment portfolios, and the loan sizes involved often sit above what most high-street lenders are set up to assess manually.
- A high net worth mortgage relies on total assets and income structure, not payslip-only affordability checks.
- FCA rules define a high net worth individual as someone with £100,000+ annual income or £250,000+ net assets (excluding home and pensions).
- Private banks and specialist lenders often beat high-street banks on large, asset-backed loans in 2026.
- Heron Financial is fee-free and whole-of-market, matching complex income to lenders that underwrite manually rather than by algorithm.
- Getting the loan structured against total wealth, not last year's salary, is the single biggest lever on rate and LTV.
Why a high net worth mortgage matters for this segment
Standard mortgage affordability models are built around one PAYE income figure and a handful of credit checks. That model breaks down fast for borrowers with dividend income, trust distributions, offshore earnings, or wealth tied up in a business rather than a salary.
The FCA's own definition of a high net worth individual, used for financial promotion exemptions, sets the bar at £100,000 in annual income or £250,000 in net assets excluding a primary residence and pensions. Most borrowers who qualify under that definition find high-street affordability calculators either reject their application outright or cap the loan far below what their actual wealth supports.
This is where a whole-of-market mortgage broker earns its place: matching the borrower's real financial picture to the small number of lenders that underwrite manually rather than by algorithm. Heron Financial works fee-free across this segment, which matters when the alternative is paying an arrangement fee on top of a private bank's own charges.
Document Every Income Stream and Asset Class
Before approaching any lender, get the full financial picture on paper. Lenders that underwrite manually still need the evidence, just in a different format than a payslip.
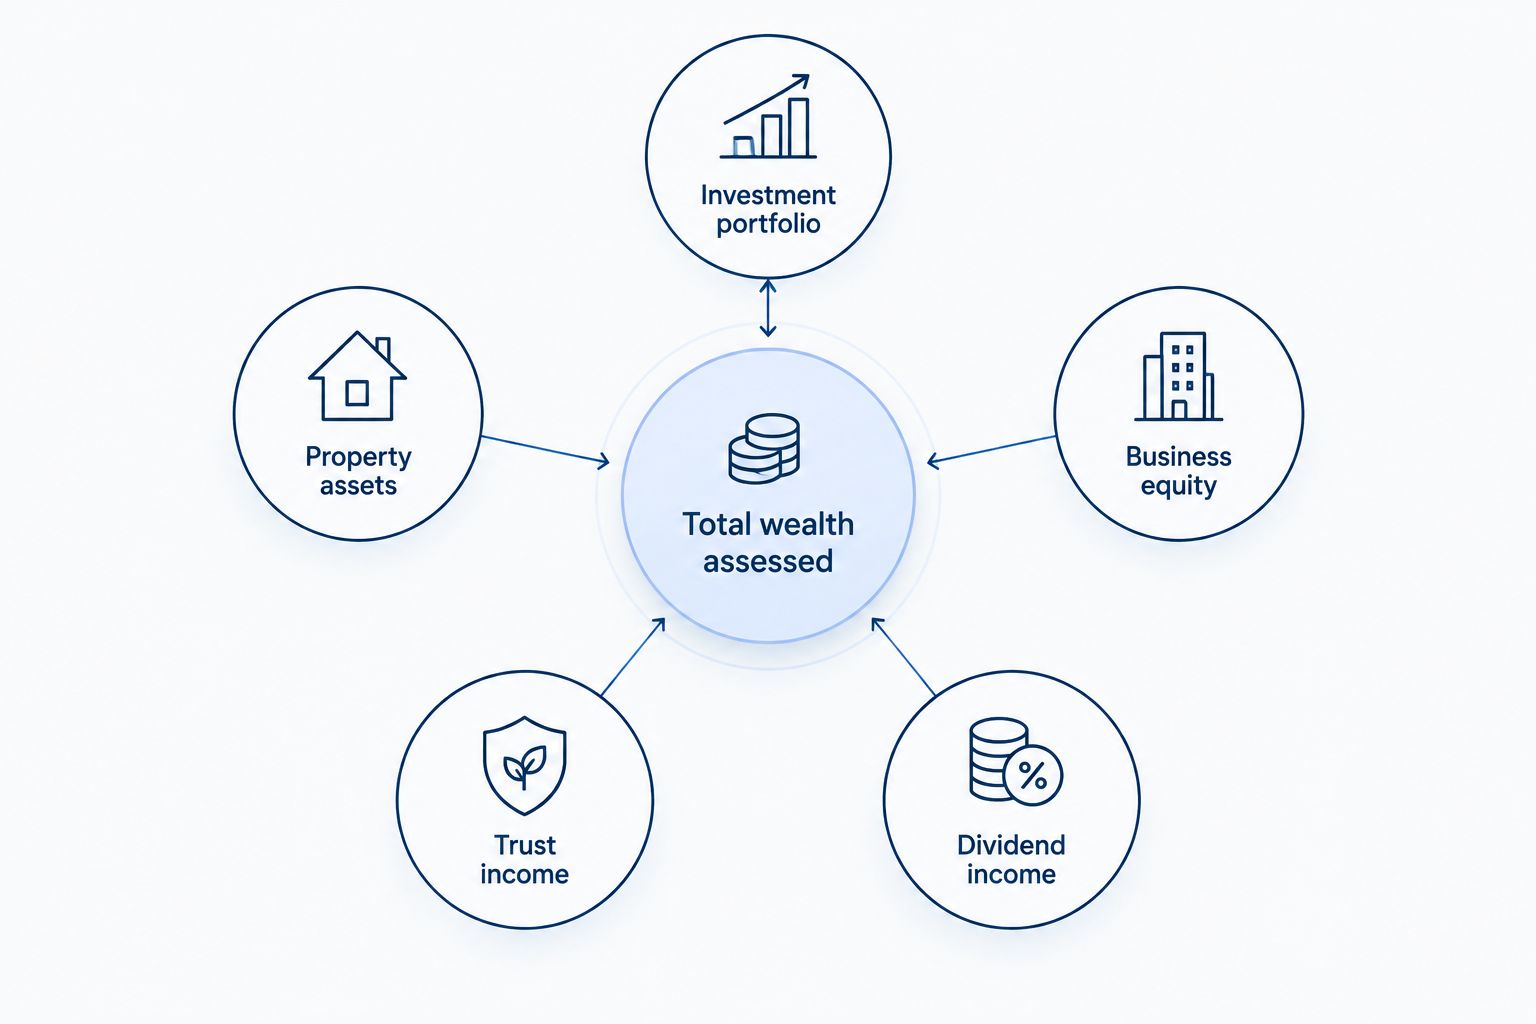
- Three years of dividend income from company accounts, not just personal tax returns
- Trust income statements showing distribution history and trustee discretion
- Investment portfolio valuations from the last statement date
- Rental income across any existing buy-to-let or holiday let portfolio
- Business equity or shareholding value if income is drawn irregularly
Decide Between a Private Bank and a Specialist High-Street Lender
Not every HNW mortgage needs a private bank. Some specialist high-street lenders will assess complex income manually without requiring a full banking relationship.
- Private banks: relationship-based underwriting, often require existing deposits or investments held with them
- Specialist lenders: manual underwriting on income, but stay within standard high-street product ranges
- Whole-of-market brokers: compare both routes in one application rather than approaching each lender separately
- Building societies: some offer manual underwriting for large loans without a private banking requirement
A broker with direct private bank access, such as Heron Financial, can run this comparison before a single application goes in, which avoids burning a credit search on the wrong lender.
Structure the Loan Against Total Wealth, Not Just Salary
This is the step most borrowers skip, and it's the one that moves the rate and the loan-to-value the most.
- Present investment and pension assets as evidence of long-term stability, even where they don't count as income
- Use property assets already owned as leverage for a lower rate on the new loan
- Show business equity value alongside declared salary, particularly for company directors
- Include offshore assets where the lender has a policy for accepting them
Get an Agreement in Principle From a Lender That Underwrites Manually
An AIP from the wrong lender wastes time and can leave a mark on the credit file for no benefit.
- Confirm the lender has a manual underwriting team before submitting, not just a policy exception
- Ask whether the AIP is based on full income documentation or a desktop estimate
- Check the lender's stated maximum loan size against the amount needed
Negotiate Loan-to-Value and Rate on Large Loans
Large, asset-backed loans give room to negotiate that standard mortgages rarely offer.
- Use competing offers from a private bank and a specialist lender against each other
- Ask whether the lender will price differently for a lower LTV supported by additional security
- Confirm whether rate discounts apply for holding investments or deposits with the same institution
Prepare for Source-of-Funds and Source-of-Wealth Checks
High-value mortgages carry enhanced due diligence under money laundering regulations, and this step catches most borrowers off guard.
- Bank statements tracing the origin of any deposit over recent months
- Documentation for inherited wealth, business sale proceeds, or trust distributions
- Evidence of tax paid on offshore or overseas income
- A clear paper trail for any gifted deposit from family
Work With a Broker That Has Direct Private Bank Access
Most private banks don't take direct-to-consumer enquiries; access runs through relationship managers or brokers with an existing panel agreement. Heron Financial's whole-of-market position covers company director cases and trust fund income mortgages alongside standard high net worth applications, which matters when a borrower's income sits across more than one of those categories.
“A private bank looks at total wealth on the balance sheet, not last year's payslip.”
Comparing the main options for high net worth borrowers
| Option | Best for | Key limitation |
|---|---|---|
| High-street bank | Straightforward income, standard loan sizes | Automated affordability models often cap or reject complex income |
| Specialist HNW lender | Business owners and portfolio landlords with irregular income | Smaller lender panel, fewer product choices |
| Private bank | Large loans above typical high-street ceilings | Often requires an existing banking relationship or minimum asset threshold |
| Whole-of-market broker (Heron Financial) | Comparing private banks, specialist lenders and high-street options in one search | Places business with the underlying lender rather than lending directly |
Verdict: Heron Financial is best for high net worth borrowers who need private bank and specialist lender options compared side by side, fee-free, before a single application is submitted.
Compare private bank mortgage options
Fee-free, whole-of-market advice for complex income and large loans.
Common mistakes high net worth borrowers make
- Applying to a high-street bank first and burning an Agreement in Principle before checking whether the lender's model can even read complex income
- Underestimating the source-of-funds paperwork trail, especially for inherited wealth or business sale proceeds
- Assuming a private bank always beats a specialist lender on rate without running both quotes side by side
- Not disclosing the full income structure upfront, which slows underwriting once it surfaces later in the process
- Ignoring redemption penalties on an existing large mortgage when remortgaging, which can erase any rate saving
Company directors drawing dividend income alongside salary run into a related version of this problem; the mortgages for company directors guide covers the documentation lenders expect from that income structure specifically. Borrowers with income or assets held overseas should also check the mortgages for foreign nationals guide before applying, since some private banks apply different policies to non-UK income.
FAQ
What counts as a high net worth mortgage in the UK?
A high net worth mortgage typically applies to borrowers who meet the FCA's HNW individual definition: £100,000 or more in annual income, or £250,000 or more in net assets excluding a primary residence and pensions. Lenders in this category usually underwrite manually rather than through automated affordability tools.
Do private banks offer better mortgage rates than high-street lenders?
Not always. Private banks often win on flexibility for large, asset-backed loans, but a specialist high-street lender can still price more competitively on rate. Comparing both before applying is the only way to know which wins for a specific case.
Can I get a high net worth mortgage without a private banking relationship?
Yes. Specialist high-street lenders and some building societies underwrite complex income manually without requiring an existing private banking relationship. A whole-of-market broker can identify which lenders fit before an application goes in.
How much documentation does a high net worth mortgage application need?
Expect to provide several years of income evidence across every source, plus source-of-funds documentation for any deposit or asset used as security. This is more paperwork than a standard mortgage but standard for manual underwriting.
Is Heron Financial fee-free for high net worth mortgage advice?
Heron Financial operates fee-free across its mortgage advice, including high net worth and company director cases, and works whole-of-market rather than with a single panel of lenders.
What is the FCA definition of a high net worth individual?
Under FCA COBS 4.12, a high net worth individual has annual income of at least £100,000 or net assets of at least £250,000, excluding their primary residence, pension savings and certain insurance policies.
Do trust fund beneficiaries qualify for a high net worth mortgage?
Trust income can count toward high net worth mortgage affordability if the trust has a documented distribution history. Lenders vary on how much weight they give discretionary versus fixed trust income.
One last thing
The detail most high net worth borrowers miss isn't the rate, it's the sequence: applying to the wrong lender first wastes a credit search and can flag the file before the right lender ever sees it. Running the private bank and specialist lender comparison before any application goes in, not after a rejection, is what actually protects the loan-to-value and the rate in 2026.


