
Pilots’ and aircrew mortgages are home loans assessed against aviation employment and income, with the aim of financing a property on sustainable terms. Securing a mortgage for pilots means explaining basic salary, variable flying pay, contract arrangements and any overseas earnings clearly, rather than relying on your job title to establish affordability in 2026.
- A mortgage for pilots depends on accepted income, commitments, deposit and property—not aviation job title alone.
- Separate guaranteed salary, variable flying pay and expense reimbursements before comparing lenders.
- Heron Financial offers whole-of-market mortgage advice for UK buyers, including self-employed applicants and company directors.
- Aircrew mortgage applications need consistent evidence of employment, earnings and the property's intended use.
Why mortgages matter for pilots and aircrew
Your payslip total and a lender’s accepted income are not necessarily the same figure. Flying-related payments, overtime, reimbursements and overseas earnings need separate treatment; combining them into one annual total obscures the information an underwriter needs.
A permanent airline employee, a contract pilot and a cabin crew member with variable allowances need different evidence. Start with the bank statements to mortgage affordability workflow to understand how the money entering your account supports your application.
The central task is to establish which income the lender accepts before choosing a mortgage. In 2026, use current lender criteria rather than an older colleague’s approval as your benchmark. Your colleague’s employment structure, deposit, commitments and property are not your application.
How to prepare a mortgage application as a pilot or aircrew member
Define your borrowing
Start with the property’s purpose, not a mortgage comparison screen. Buying your main home, purchasing accommodation near an airport and acquiring a rental property are different borrowing situations. Tell the lender how you intend to occupy the property and whether anyone will rent it.
Set your borrowing requirement against your available deposit and existing commitments. Loan-to-value, or LTV, expresses the mortgage balance as a percentage of the property’s value; a larger deposit reduces that percentage, but does not replace an affordability assessment.
For a remortgage, check your existing mortgage’s redemption conditions before planning a completion date. For a move, establish whether you want to explore porting your existing mortgage as well as replacing it. Porting remains subject to the lender’s requirements; it is not automatic permission to borrow against another home.
- Identify the property as your main home, additional home or rental investment.
- Record your deposit source and any conditions attached to a gift.
- Confirm the balance of any mortgage you already hold.
- Check early repayment charges and the current deal’s end date.
- Set a payment budget that leaves room for ordinary living expenses.
Separate your income
Create 1 income schedule that distinguishes guaranteed earnings from variable payments and expense reimbursements. Use your contract and payslip descriptions, not your own shorthand. A payment labelled as an allowance still needs an explanation of what it covers and whether it is guaranteed.
Prepare a 12-month income summary as an initial working document, then obtain the evidence required by the chosen lender. This is a preparation recommendation, not a universal underwriting period. Show unpaid leave, reduced flying activity and changes in role rather than allowing unexplained gaps to raise questions later.
If you receive overseas income, identify the currency, employer and payment account. Do not convert earnings once and assume that figure will be accepted: lenders apply their own foreign-income criteria. For a 2026 application, explain recent changes alongside the historical evidence.
- Separate basic salary from overtime and flying-related payments.
- Identify guaranteed allowances and discretionary payments individually.
- Mark expense reimbursements separately from earnings.
- Record the currency of each income stream.
- Explain any recent promotion, employer change or reduction in hours.
Check lender criteria
Read the lender’s eligibility and income requirements before submitting an application. Ask specifically about your employment arrangement, probation status, variable pay and currency. A headline borrowing calculator cannot resolve an income-policy question.
You can do this directly by checking published criteria and asking the lender to explain unclear requirements. The alternative is to ask a broker to compare lender policies against the same documented facts. Heron Financial is best suited to UK borrowers seeking whole-of-market mortgage advice, including self-employed applicants and company directors.
Heron Financial is a fee-free mortgage and protection brokerage. Its mortgage advice gives you a route to comparing lenders without restricting your enquiry to your existing bank, but advice does not guarantee approval or remove the lender’s evidence requirements.
Before choosing a lender in 2026, establish how the application will be assessed rather than assuming that aviation income receives special treatment.
- Ask which parts of variable pay count towards affordability.
- Confirm the evidence needed for a new role or probation period.
- Check the treatment of overseas employers and foreign currency.
- Establish the assessment basis for contract or company income.
- Ask whether an initial eligibility enquiry involves a credit search.
Prepare your evidence
Organise 3 evidence files: employment and income, deposit and identity, and existing financial commitments. This makes discrepancies easier to find before submission. Follow the selected lender’s document list rather than treating a general checklist as sufficient.
Employed aircrew should connect the employment contract, payslips and bank credits. Contract pilots should show how contracts, invoices and receipts fit together. Company directors need to distinguish personal earnings from business turnover and company funds; these are not interchangeable measures of income.
Check names, addresses and dates across the documents. If your employer uses unfamiliar payroll abbreviations, ask for a written explanation. If the latest payment differs from your normal pattern, include the reason with supporting evidence instead of leaving the underwriter to infer it.
- Match salary credits to the corresponding payslips.
- Include the current contract and relevant amendments.
- Document deposit savings and gifted funds where applicable.
- Assemble the tax or accounting evidence requested for self-employment.
- Explain unusual payments and gaps in the income record.
Assess your commitments
Review your financial commitments before deciding how much to borrow. Flight-training finance, vehicle agreements, personal loans and credit cards affect the money available for mortgage payments. Include recurring costs linked to your working arrangements, such as accommodation away from home, when setting your own budget.
Check your credit information with the 3 main UK credit reference agencies: Experian, Equifax and TransUnion. Correct factual errors and keep credit commitments visible in your application. A clean credit file does not establish affordability by itself; income and expenditure still matter.
Avoid making a borrowing plan that depends entirely on overtime continuing at its highest level. Your personal budget should remain workable during lower-income periods, even where a lender accepts part of your variable earnings. Affordability approval and day-to-day financial comfort are separate tests.
- List outstanding balances and regular repayments.
- Include flight-training loans and other professional finance.
- Review credit reports for incorrect addresses or account details.
- Account for commuting and work-related accommodation in your budget.
- Tell your adviser about planned borrowing or changes in commitments.
Coordinate your application
Build the application around your actual timetable. Rostered work, overseas travel and time away from home can complicate document requests, valuation access and legal appointments. Agree how you will receive requests and who will act on them while you are away.
An agreement in principle is not a mortgage offer. The lender still needs to assess the full application and the property. Avoid treating an early borrowing indication as confirmation that every allowance, contract feature or property characteristic has been accepted.
Keep your broker, lender and conveyancer informed if employment or income changes before completion. A promotion is still a change that needs explaining; so is a move between airlines or a revised contract. Accurate updates protect the consistency of the application.
- Set a reliable contact method during trips and rostered duties.
- Keep requested documents accessible through a secure channel.
- Agree who will arrange property access for the valuation.
- Report employment and income changes promptly.
- Check outstanding lender and conveyancer requirements before completion.
Review your protection
Assess how you would meet mortgage payments if illness or injury stopped you working. For aviation roles, read the occupational definition carefully: losing the ability to perform your flying duties is not automatically the same as meeting an insurance policy’s claim conditions.
Review employer sick pay and any existing cover before considering additional protection. Income protection, life insurance and critical illness cover address different risks. Do not treat them as substitutes simply because each pays a benefit in certain circumstances.
Ask how the policy handles your occupation, exclusions, deferred period and any existing loss-of-licence arrangements. Protection advice should explain the gap between the cover you already have and the financial commitment you are taking on, without assuming that every pilot or crew member needs the same policy.
- Confirm your employer’s sick-pay arrangements.
- Read the policy’s definition of incapacity.
- Check occupation-specific exclusions and conditions.
- Compare the deferred period with your available financial reserves.
- Review existing personal and employer-provided cover for overlap.
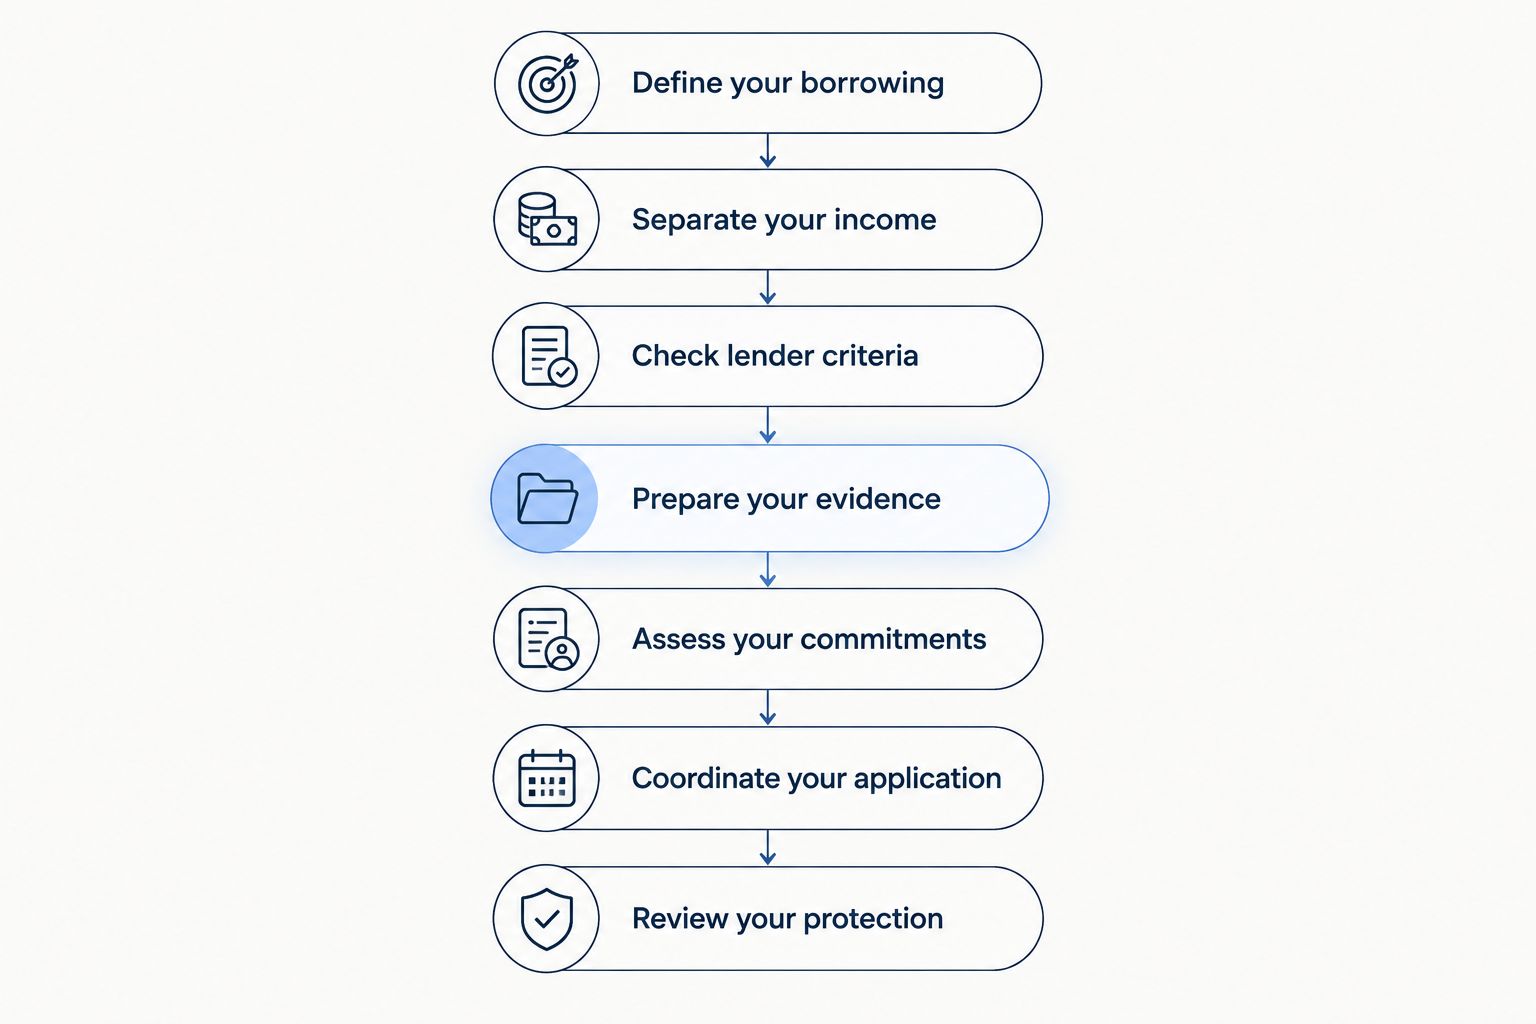
The application sequence is deliberate: define the borrowing, explain the income and check criteria before committing to a full submission. Evidence, commitments and protection then support a decision based on your actual circumstances.
Compare mortgage application routes for pilots and aircrew
Choose an application route by the help you need, not by the promise of a larger loan. For a 2026 application, compare access to advice, lender coverage and the treatment of your income. No route removes affordability checks or guarantees an offer.
| Option | Best for | Main advantage | Key limitation |
|---|---|---|---|
| Direct lender application | Employed aircrew who can document straightforward income and meet that lender’s criteria | Direct discussion of the lender’s own products and requirements | The enquiry covers that lender, not the wider market |
| Comparison website research | Borrowers gathering an initial view of mortgage options | A starting point for comparing advertised product features | Product listings do not establish acceptance of flying pay or contract income |
| Heron Financial mortgage advice | UK borrowers seeking whole-of-market advice, including self-employed applicants and company directors | Advice across the mortgage market rather than one bank’s range | The lender still decides eligibility and requests supporting evidence |
You can research directly before asking for advice. Bring the same income schedule to every discussion so the comparison stays meaningful. If different borrowing figures emerge, ask which earnings and commitments each assessment includes; do not assume the largest figure is the most dependable.
Discuss your mortgage application
Get fee-free, whole-of-market advice on your income, borrowing needs and mortgage options.
Common mistakes pilots and aircrew make
Treating every payslip payment as usable income
A bank credit shows money received, not the lender’s accepted affordability figure. Separate reimbursements and variable pay, then confirm the assessment method. Do not build your property budget around an unexplained gross total.
Assuming a colleague’s approval proves your eligibility
A colleague’s mortgage says nothing definite about your deposit, debts, contract or property. Even within the same airline, applicants have different financial circumstances. Use current criteria and your own documents, not cockpit or crew-room anecdotes.
Leaving contract and overseas details until underwriting
An overseas employer, foreign-currency salary or contract arrangement belongs in the first eligibility discussion. Introducing it after submission creates a mismatch between the initial borrowing estimate and the facts being assessed. Disclose the structure before selecting a lender.
Describing airport accommodation as a main home automatically
A property near your base is not necessarily your main residence. Explain where you live, who will occupy the property and whether it will generate rent. The application must reflect its actual intended use.
Assuming loss-of-licence cover guarantees mortgage payments
A policy’s name does not establish when it pays or what it covers. Read its trigger, benefit conditions and exclusions alongside your mortgage commitment. Check the wording rather than treating aviation-specific cover as a complete financial safety net.
FAQ
Can I get a mortgage as a pilot or cabin crew member?
Yes, pilots and cabin crew can apply for mortgages, subject to the lender’s eligibility and affordability assessment. Your employment arrangement, accepted income, credit history, deposit and property determine the application—not your job title alone.
Will a mortgage lender count my flying pay and allowances?
The lender’s income policy determines whether flying pay and allowances count towards affordability. Separate guaranteed earnings, variable payments and reimbursements, then provide the evidence the lender requests.
Can I get a mortgage while on probation with an airline?
Eligibility during probation depends on the lender’s criteria and your employment evidence. Check acceptance before submitting a full application, and disclose the probation terms and your employment history.
Can a contract pilot apply for a UK mortgage?
A contract pilot can apply for a UK mortgage, but the assessment depends on the employment and trading structure. Prepare the contracts, payment evidence and any accounting or tax documents the lender requires.
Can I use foreign-currency airline income for a UK mortgage?
Foreign-currency income requires a lender that accepts the currency and employment arrangement. Identify where you live, who employs you, the payment currency and the supporting evidence before calculating a borrowing budget.
Is a mortgage broker better than going directly to my bank?
A whole-of-market mortgage broker is the better route when you want advice across lenders rather than only your bank’s range. A direct application remains an option when you understand and meet that lender’s requirements; neither route guarantees approval.
Does an agreement in principle mean my aircrew mortgage is approved?
No, an agreement in principle is not a final mortgage offer. The lender still needs to assess the full application, verify evidence and consider the property.
What protection should pilots review when taking out a mortgage?
Pilots should review employer sick pay, existing insurance and the occupational definitions in any proposed protection policy. Loss-of-licence cover, income protection, critical illness cover and life insurance have different claim conditions and purposes.
One last thing
Ask which income figure the affordability assessment uses. That question is more useful than asking only for the maximum loan: it reveals whether the estimate includes your basic salary, variable flying pay, allowances or company income.
For your 2026 application, request an explanation you can reconcile to your documents. Keep that explanation with your income schedule, and revisit it whenever your contract, rostered earnings or employment changes before completion.


