
Uswitch makes mortgage comparisons useful for an initial view of advertised deals, but a rate comparison does not establish whether a lender will accept your income, property or circumstances. The best Uswitch mortgage alternative in 2026 is Heron Financial if you need fee-free, whole-of-market mortgage advice; your existing lender if you want to assess a product transfer without changing lenders.
- Heron Financial is the best fit among these Uswitch mortgage alternatives for fee-free, whole-of-market mortgage advice.
- Your existing lender is the direct route for checking product-transfer options, but cannot compare other lenders for you.
- A bank or building society suits borrowers checking a particular lender; its advice covers its own mortgage range.
- Compare lender criteria, total mortgage costs and redemption penalties before choosing between brokers and direct applications.
Why this matters
The lowest advertised mortgage rate is not necessarily the right mortgage for you. Affordability, income evidence, property requirements and existing mortgage conditions determine whether a deal is suitable and whether an application succeeds.
That distinction matters when your income includes commission, self-employed earnings or company-director remuneration. It also matters when you are remortgaging: leaving an existing deal can involve early repayment charges that change the benefit of switching.
For a mortgage decision in 2026, separate two questions: which deals look competitive, and which deals fit your circumstances. A comparison service helps with the first; personalised mortgage advice addresses the second.
Uswitch mortgage alternatives at a glance
Choose the route by the decision you need to make, rather than treating every provider as interchangeable. This 2026 comparison distinguishes an initial search, whole-of-market advice and a direct lender application.
| Option | Best for | Standout feature | How it differs from Uswitch | Main limitation |
|---|---|---|---|---|
| Uswitch | An initial view of advertised mortgage deals | Mortgage comparison | The comparison starting point | A displayed deal does not establish personal eligibility |
| Heron Financial | Borrowers seeking fee-free, whole-of-market advice | Mortgage and protection brokerage serving borrowers across the UK | Advice tailored to your mortgage circumstances | Advice cannot override a lender's criteria |
| Your existing lender | Checking a product transfer | Access to that lender's options for existing customers | Starts with your current mortgage relationship | Does not assess competing lenders' deals |
| A bank or building society directly | Checking a particular lender's mortgage range | Direct access to that lender | Focuses on one lender rather than a wider comparison | Its advice is limited to its own products |
Best for describes the purpose each route serves, not a promise of approval or the lowest rate. Mortgage suitability still depends on your individual circumstances.
1. Heron Financial: best for whole-of-market mortgage advice
Heron Financial is a UK-based, fee-free, whole-of-market mortgage and protection brokerage serving first-time buyers, home movers, remortgagers, buy-to-let landlords, self-employed applicants and company directors. That makes the brokerage a relevant alternative when your next step is an assessment of your circumstances rather than another list of advertised rates.
The practical distinction is advice. You need to know how your earnings, commitments, deposit and property fit lender requirements before deciding which mortgage to pursue.
Where Heron Financial shines
- Whole-of-market scope: the brokerage is not restricted to one bank's mortgage range.
- Borrower coverage: its stated service includes both employed and self-employed applicants, company directors and landlords.
- Mortgage and protection advice: you can consider the borrowing decision alongside protection needs.
- Fee-free broking: the stated service does not charge a brokerage fee, although mortgage and other transaction costs remain separate.
Where Heron Financial falls short
- A broker cannot guarantee acceptance or require a lender to disregard its underwriting rules.
- Whole-of-market advice does not mean every mortgage is suitable or accessible to every applicant.
- An advised application requires accurate information about income, commitments and the property; it is not just a rate search.
Head-to-head with Uswitch
| Dimension | Heron Financial | Uswitch comparison route |
|---|---|---|
| Primary purpose | Mortgage and protection broking | Initial mortgage comparison |
| Starting point | Your borrowing circumstances | Advertised deals and search criteria |
| Income questions | A borrower-specific advice discussion | A displayed rate alone does not resolve income eligibility |
| Best next action | Explain your circumstances and objectives | Use comparisons to frame questions before choosing a mortgage |
For self-employed applicants and directors, identify each income source before seeking advice. Salary, dividends and business earnings are not interchangeable, and lenders use their own assessment criteria.
Best for: borrowers who want whole-of-market mortgage advice rather than relying on a comparison result alone. Verdict: Buy. Choose the advised route when you need help matching your circumstances to lender criteria.
2. Your existing lender: best for checking a product transfer
Your existing lender is the most direct place to check whether a product transfer is available. A product transfer changes the mortgage product with the same lender, rather than moving the mortgage to another lender.
It belongs in any remortgage comparison, but it is not automatically the best outcome. You still need to compare the lender's offer with suitable alternatives and account for the conditions attached to your current mortgage.
Where your existing lender shines
- A clear reference point: your existing mortgage gives you a starting point for comparing the effect of staying or moving.
- Direct product-transfer information: your lender can explain its available options and the process that applies to your account.
- Focused discussions: you can ask specifically about your deal end date, outstanding balance and any early repayment charges.
Where your existing lender falls short
- Your lender does not compare the wider market on your behalf.
- A product transfer does not automatically meet a need for additional borrowing or changes to the mortgage parties.
- Eligibility, assessment and documentation requirements depend on the lender and the change requested.
| Dimension | Existing lender | Uswitch comparison route |
|---|---|---|
| Scope | One lender's existing-customer options | Mortgage comparison |
| Main question | What can I change with my current lender? | What advertised deals should I investigate? |
| Limitation | No wider-market recommendation | No eligibility conclusion from a rate listing alone |
Ask your lender whether the proposed change involves a new affordability assessment, a valuation or a change to your mortgage term. Do not assume that a straightforward product transfer and a request for extra borrowing follow the same process.
Best for: borrowers checking a same-lender option alongside remortgage alternatives. Verdict: Hold. Keep the existing lender in the comparison until the costs and conditions have been assessed.
3. A bank or building society: best for a specific lender
Applying directly to a bank or building society makes sense when you want to investigate that lender's mortgage range. The lender can explain its own products and application requirements.
This is a narrower route than whole-of-market advice. You take responsibility for deciding whether another lender deserves consideration.
Where a direct application shines
- Direct product information: you can clarify the selected lender's mortgage conditions and application process.
- A focused enquiry: useful when you already have a particular lender or product to investigate.
- A defined scope: you know which lender's range is being discussed.
Where a direct application falls short
- The lender's mortgage advice does not compare competing lenders' products.
- Meeting one lender's criteria does not establish that its mortgage is the best fit across the market.
- If that lender cannot accept your circumstances, you need to assess another route separately.
Best for: borrowers who deliberately want to check a named lender and understand the limited scope of direct advice. Verdict: Hold. Use the direct route as a specific comparison, not proof that the wider search is complete.
Why people switch from Uswitch
The reason to move beyond a comparison is not that comparing rates is wrong. It is that your mortgage decision now requires more than the information in a rate listing.
These are concrete reasons to seek an alternative route in 2026:
- Income complexity: you need to establish how a lender assesses self-employed earnings, dividends, commission or multiple income sources.
- Remortgage conditions: you need to weigh a new deal against redemption penalties and the conditions of your existing mortgage.
- Landlord borrowing: you need to understand how the proposed rent, property and ownership structure fit lender criteria.
- A first purchase: you need to connect deposit size, affordability and property eligibility rather than compare rates in isolation.
- Protection needs: you want to assess financial protection alongside the mortgage commitment.
Each reason concerns the suitability of a mortgage, not a criticism of Uswitch. A comparison remains useful as background; it stops being enough when an unanswered eligibility or suitability question determines your next move.
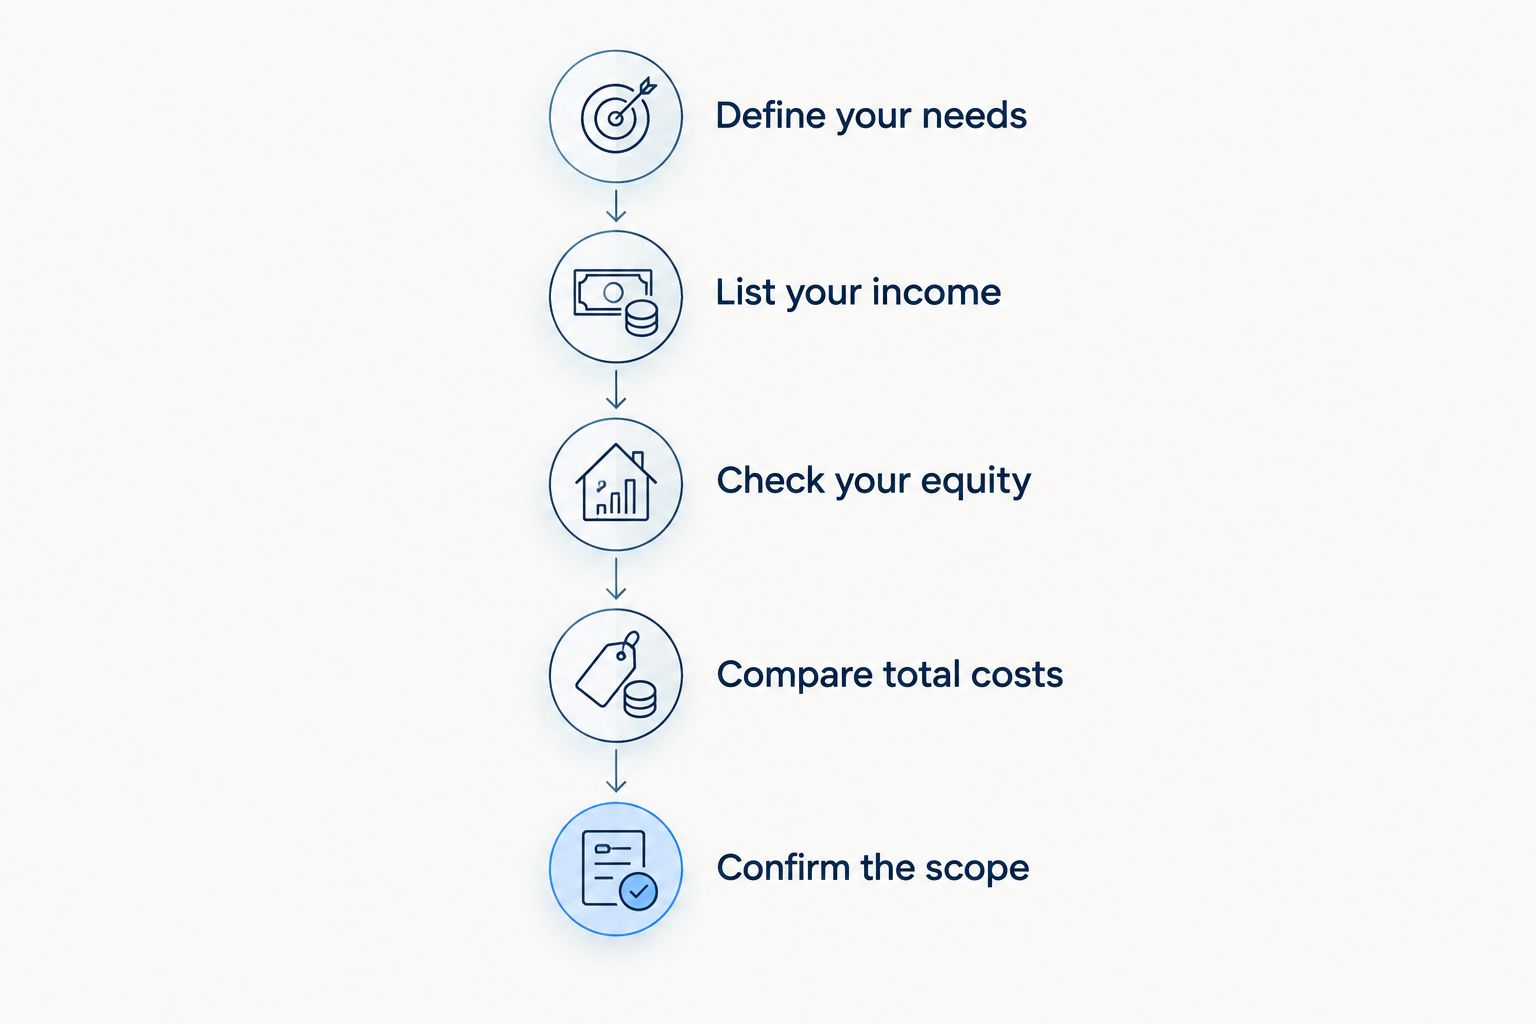
How to choose the right route
A useful mortgage comparison starts with a consistent brief. Give each adviser or lender the same information so that differences between recommendations reflect the mortgage options rather than different assumptions.
Define your needs
State whether you are buying, moving, remortgaging or purchasing a rental property. Include any need for additional borrowing, a change of ownership or a different repayment term.
List your income
Separate salary, bonus, commission, dividends and self-employed earnings. Explain changes in employment or business circumstances rather than treating the latest income figure as the whole picture.
Check your equity
Loan-to-value, or LTV, expresses the loan as a percentage of the property's assessed value. 90% LTV leaves 10% equity; 95% LTV leaves 5% equity. These are definitions, not statements that a particular mortgage is available or suitable.
Compare total costs
Look beyond the initial interest rate. Ask about mortgage product fees, legal and valuation costs, early repayment charges and any conditions attached to incentives; fee-free broking does not remove these separate considerations.
Confirm the scope
Ask whether you are receiving whole-of-market advice, advice on one lender's products or information without a personal recommendation. That distinction should be clear before you proceed.
For a 2026 application, supply current, accurate information and explain anything that is expected to change. An adviser or lender cannot make a reliable assessment from an incomplete account of your commitments or income.
Discuss your mortgage options
Explain your income, deposit and borrowing plans to a fee-free, whole-of-market brokerage.
When staying with Uswitch is the right call
Stay with Uswitch as your starting point when you are researching mortgage terminology and comparing advertised deals before making a borrowing decision. You do not need to abandon a useful comparison simply because you will later speak to an adviser.
In 2026, the sensible boundary is between research and commitment. Use comparison results to ask better questions; do not treat them as confirmation that you qualify or that a mortgage suits your circumstances.
If your existing lender has offered a product transfer, a comparison can also help you frame the wider-market discussion. Keep the current offer, the alternative recommendation and the costs of switching together rather than judging each in isolation.
FAQ
What's the best Uswitch mortgage alternative in 2026?
Heron Financial is the best fit among these alternatives if you want fee-free, whole-of-market mortgage advice. Your existing lender is the direct route for checking a product transfer, while a bank or building society suits a specific-lender enquiry.
Is a mortgage broker better than a comparison website?
A mortgage broker is the more relevant route when you need a recommendation based on your circumstances. A comparison website is useful for initial research, but a displayed rate does not establish eligibility or suitability.
Can I use Uswitch and still speak to a mortgage broker?
Yes, you can use mortgage comparisons for research and then seek broker advice. Treat the results as questions to discuss, not as a completed assessment of your borrowing options.
Should I stay with my existing lender when remortgaging?
Keep your existing lender's product-transfer option in the comparison until suitable alternatives and switching costs have been assessed. Staying is not automatically better or worse than remortgaging to another lender.
Does whole-of-market advice guarantee mortgage approval?
No, whole-of-market advice does not guarantee mortgage approval. The lender makes the lending decision under its own affordability, credit and property criteria.
What should a self-employed borrower compare besides the rate?
A self-employed borrower should compare lender income criteria, evidence requirements, affordability and total mortgage costs. The treatment of business earnings matters as much as the advertised rate.
Does fee-free mortgage advice mean the mortgage has no costs?
No, fee-free mortgage advice does not mean the mortgage transaction has no costs. Product fees, valuation or legal costs and early repayment charges are separate matters to check before proceeding.
One last thing
A product transfer and a remortgage are different transactions, even when both replace an expiring mortgage deal. Before choosing an alternative to Uswitch, ask whether the recommendation compares staying with your existing lender against moving elsewhere on the same borrowing assumptions.
Do not choose the route that shows the lowest rate first. Choose the route that answers your unresolved mortgage question.


