
MoneySavingExpert is a useful starting point for mortgage guides and calculators, but general information does not replace advice on your application. The best MoneySavingExpert mortgage alternative in 2026 is Heron Financial if you need whole-of-market mortgage advice; MoneyHelper is the better choice if you need impartial guidance before choosing an adviser.
- For moneysavingexpert mortgage alternatives for first time buyers, choose Heron Financial for whole-of-market mortgage advice.
- MoneyHelper is best for impartial mortgage guidance before you choose an adviser.
- Going directly to a lender suits buyers who want to assess that lender’s mortgages, not compare the market.
- Keep MoneySavingExpert for background reading; use personalised advice when lender eligibility becomes the deciding issue.
Why this matters
Your first mortgage involves two different decisions: understanding how borrowing works and finding a mortgage that fits your circumstances. A guide helps with the first. A broker or lender assesses the second using your income, commitments, deposit and proposed property.
Choose the service that solves your next problem, not the website with the longest list of mortgages. If you are still learning, independent guidance is useful. If you need to know how a lender will treat commission, self-employed earnings or parental leave, move to advice about your actual circumstances.
This comparison separates information, whole-of-market brokerage and direct lender applications. They are different services, not interchangeable versions of the same thing.
MoneySavingExpert alternatives at a glance
| Option | Best for | Standout feature | How it differs from MoneySavingExpert | Main limitation |
|---|---|---|---|---|
| MoneySavingExpert | Learning mortgage basics and preparing questions | Consumer-focused guides and calculators | The reference point: information before an application | General content does not assess your individual eligibility |
| Heron Financial | First-time buyers seeking whole-of-market mortgage advice | Mortgage and protection brokerage serving buyers across the UK | A brokerage service rather than a consumer information website | A broker does not make the lender’s approval decision |
| MoneyHelper | Impartial guidance before choosing an adviser | Government-backed money guidance | A broader guidance service, rather than mortgage product selection | Guidance is not a personalised mortgage recommendation |
| A direct mortgage lender | Buyers assessing a particular lender’s mortgages | Direct discussion of that lender’s criteria and application process | A route to applying, rather than background reading | It does not compare competing lenders’ products |
No single option replaces every part of MoneySavingExpert. Keep the information source you find useful, then add the right service when you need an affordability assessment or a mortgage recommendation.
1. Heron Financial: best for whole-of-market mortgage advice
Heron Financial is a UK-based, whole-of-market mortgage and protection brokerage serving first-time buyers, including self-employed applicants and company directors. Its service fits buyers who need advice about their own circumstances rather than another general mortgage guide. It is particularly relevant when your next question is which lender can assess your application, not what a mortgage term means.
Best for: First-time buyers who want a broker to assess their circumstances and recommend a suitable mortgage.
Where the brokerage shines
- Individual circumstances: The brokerage serves first-time buyers, self-employed applicants and company directors, rather than addressing only straightforward employed income.
- Whole-of-market advice: You can discuss mortgage options across the market instead of restricting the conversation to one bank’s range.
- Mortgage and protection together: You can consider the borrowing decision alongside protection needs, while keeping those decisions distinct.
- UK coverage: The service serves applicants across the UK.
Whole-of-market is not a promise that every mortgage available directly from every lender will be included. Ask your adviser to explain the scope of the recommendation and whether any direct-only products sit outside it.
Where the brokerage falls short
- It cannot approve your mortgage: The lender decides whether to lend, subject to its underwriting and property assessment.
- Advice needs evidence: You still need to provide accurate information and supporting documents. An adviser cannot substitute for missing income or deposit evidence.
- It is not a general research library: If you only want definitions and calculators, MoneySavingExpert or MoneyHelper addresses that need more directly.
Head-to-head: brokerage versus MoneySavingExpert
| Dimension | Heron Financial | MoneySavingExpert |
|---|---|---|
| Main purpose | Mortgage and protection brokerage | Consumer information and mortgage research |
| Starting point | Your individual circumstances | General explanations and tools |
| Mortgage selection | Whole-of-market advice | Information that helps you research options |
| Approval authority | The chosen lender decides | Reading a guide does not secure approval |
For your 2026 purchase, start the advice conversation with your income structure, deposit source and property plans. Do not begin with a request for the lowest advertised rate before establishing whether the lender’s criteria fit.
Verdict: Choose the brokerage when you need a personalised mortgage recommendation; keep MoneySavingExpert as supporting reading.
2. MoneyHelper: best for impartial mortgage guidance
MoneyHelper provides government-backed money guidance, including information about mortgages and buying a home. It is useful when you need to understand the decisions ahead before choosing a broker or approaching a lender. It is a guidance service, not a replacement for a personalised mortgage recommendation.
Best for: First-time buyers who want impartial explanations and help preparing questions.
Where MoneyHelper shines
- Preparation: Use its guidance to understand affordability, mortgage types and the responsibilities of home ownership.
- Broader finances: Consider the mortgage alongside budgeting and other financial commitments.
- Clear separation from lending: Guidance helps you understand the decision without being a lender’s product application.
Where MoneyHelper falls short
- No individual product recommendation: General guidance does not establish which mortgage is suitable for you.
- No lender approval: It cannot determine whether an underwriter will accept your income or property.
- Another step remains: Once you understand the basics, you still need to choose an application route.
Head-to-head: MoneyHelper versus MoneySavingExpert
| Dimension | MoneyHelper | MoneySavingExpert |
|---|---|---|
| Main purpose | Impartial money guidance | Consumer information and research |
| Mortgage role | Explains borrowing and home-buying decisions | Provides mortgage guides and calculators |
| Individual recommendation | Not a substitute for mortgage advice | Not a substitute for mortgage advice |
| Best use | Preparing your finances and questions | Researching terminology and options |
MoneyHelper is not automatically better than MoneySavingExpert. Choose the explanation you understand most clearly, then move beyond general guidance when your question depends on lender criteria.
Verdict: Choose MoneyHelper for preparation; skip it as a substitute for personalised mortgage advice.
3. A direct mortgage lender: best for assessing one lender
A direct mortgage lender is an alternative application route, not another comparison website. You discuss your circumstances with the lender and assess mortgages within its own range. That gives you a focused conversation, but not a whole-of-market comparison.
Best for: Buyers who want to assess a particular lender and understand the limits of that approach.
Where a direct lender shines
- Focused criteria discussion: Ask how that lender treats your income, deposit and property.
- Direct application route: Deal with the organisation making the lending decision.
Where a direct lender falls short
- Restricted comparison: Another lender’s criteria or mortgage structure might fit your circumstances better.
- Repeated research: Comparing several lenders directly means gathering and checking information yourself.
| Dimension | Direct lender | MoneySavingExpert |
|---|---|---|
| Main purpose | Assess and process applications for its mortgages | Explain mortgages and support research |
| Product scope | That lender’s range | General information about options |
| Eligibility | Assessed against that lender’s criteria | Not established by reading guidance |
For a 2026 application, ask whether an initial eligibility check uses a soft or hard credit search before authorising it. Do not treat several speculative applications as a comparison method.
Verdict: Choose a direct lender deliberately; skip this route if you expect whole-of-market advice.
Why people move beyond MoneySavingExpert
The reason to add another service is not that MoneySavingExpert becomes unhelpful. It is that your question changes from general education to an individual lending decision.
Your income needs interpretation
A salary, commission payment, company dividend and self-employed profit are not interchangeable evidence. Lenders apply their own criteria to income, so a calculator result does not establish how your application will be assessed.
If your earnings fluctuate, explain the pattern before discussing mortgage products. The guide to using commission income for a mortgage addresses a question that a general borrowing estimate cannot settle.
Your deposit needs context
Loan-to-value, or LTV, expresses the mortgage as a percentage of the property value used by the lender. At 90% LTV, the remaining 10% must come from your contribution; at 95% LTV, that contribution is 5%. These are mathematical relationships, not confirmation that you qualify for a mortgage at either level.
Your deposit source matters too. Explain whether it comes from savings, a gift or another source, and ask what evidence the lender requires.
Your property affects the decision
Borrower affordability is only part of mortgage assessment. The lender also considers the property offered as security.
Tell your adviser or lender about the property type, tenure and any known issues before treating an agreement in principle as reassurance about the purchase. A borrowing indication does not settle the property assessment.
You need a recommendation, not another shortlist
Reading more product summaries will not resolve a question about suitable repayment structure or acceptable income evidence. Move to advice when the unresolved issue is personal to your application. Continue using guides to understand the adviser’s explanation and challenge anything unclear.
How to choose your next step in 2026
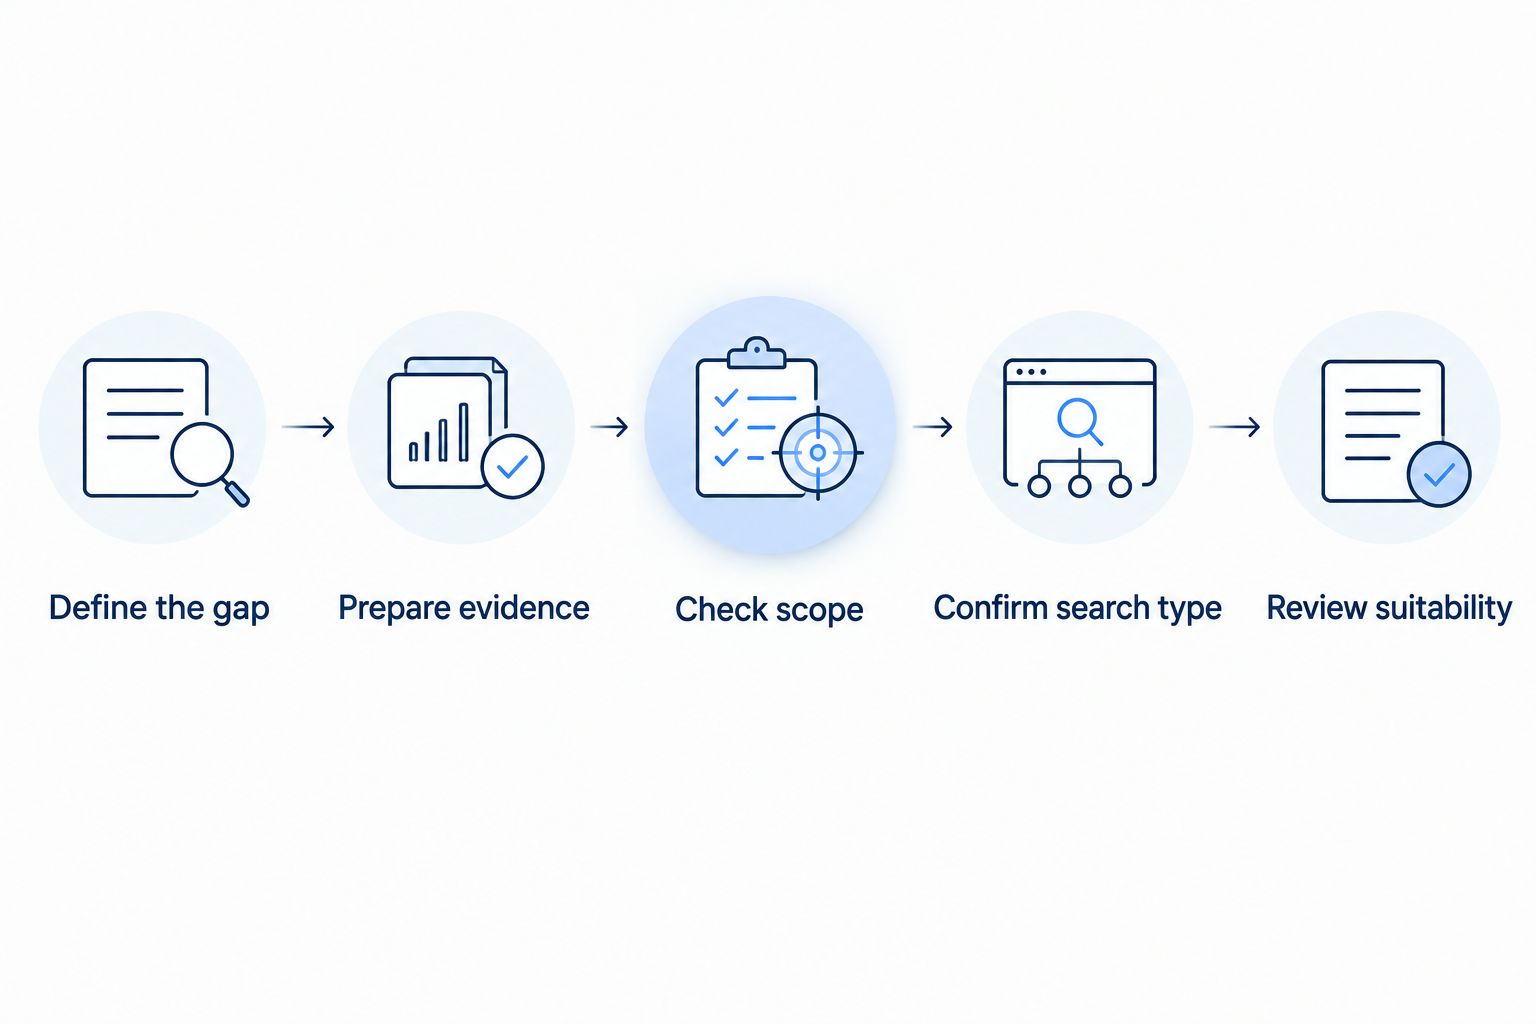
Choose the route in this order. Each step answers a different question, so you avoid treating a calculator estimate as an application decision.
- Define the gap. Write down whether you need general guidance, individual advice or assessment by a particular lender.
- Prepare evidence. Gather the income, deposit and commitment information needed to explain your circumstances accurately.
- Check scope. Ask whether the service provides guidance, whole-of-market advice or access only to one lender’s mortgages.
- Confirm search type. Before an eligibility check or application, establish what credit search will take place.
- Review suitability. Ask why the recommended mortgage fits your circumstances and what restrictions matter to you.
At the recommendation stage, ask about repayment type, mortgage term, early repayment charges and what happens when an initial deal ends. Keep these questions separate from whether the lender will accept the application: eligibility and suitability are related, but they are not the same decision.
Discuss your first mortgage
Ask about whole-of-market mortgage advice for your income, deposit and first-home plans.
When staying with MoneySavingExpert is the right call
Stay with MoneySavingExpert when you are learning terminology, exploring mortgage structures or preparing questions before an advice appointment. You do not need to abandon useful information simply because you will use a broker later.
For a 2026 first-home purchase, the sensible distinction is between research and recommendation. Use guides to become an informed borrower; use the appropriate adviser or lender to assess your circumstances.
MoneySavingExpert remains useful alongside advice, not instead of individual eligibility assessment.
FAQ
What’s the best MoneySavingExpert mortgage alternative for first-time buyers?
Heron Financial is the best fit in this comparison for first-time buyers seeking whole-of-market mortgage advice. MoneyHelper is the better fit for impartial guidance before choosing an adviser.
Is MoneySavingExpert a substitute for a mortgage broker?
No, general mortgage guides and calculators do not replace personalised mortgage advice. Use them to understand the process and prepare questions about your circumstances.
Is MoneyHelper better than MoneySavingExpert for buying my first home?
Neither is universally better: both help you understand mortgage decisions. Choose MoneyHelper for impartial money guidance, and use MoneySavingExpert where its guides and calculators answer your research questions.
Should I go directly to my bank for a first mortgage?
Go directly to a bank if you want to assess that bank’s mortgage range. Use whole-of-market advice if you want a recommendation that considers options beyond one lender.
Does whole-of-market mean every mortgage is included?
No, whole-of-market advice should not be read as a guarantee that every direct-only mortgage is included. Ask the adviser to explain the scope of the products considered.
Can a mortgage calculator tell me whether I’ll be accepted?
No, a calculator provides an estimate rather than lender approval. The lender assesses your evidence, credit profile, commitments and proposed property against its criteria.
What should I prepare before speaking to a mortgage adviser in 2026?
Prepare accurate information about your income, commitments, deposit source and intended property. Ask which supporting documents are required for your employment or self-employed circumstances.
One last thing
An agreement in principle is not a completed mortgage offer. Before you rely on it, ask what has actually been checked and what still depends on underwriting or the property assessment.
That question is more useful than asking which website is best. It tells you how much confidence to place in the next step of your purchase.
Your home may be repossessed if you do not keep up repayments on your mortgage.


